Mexico’s Metal Processing Industry: Key Growth Sectors and Supply Chain Risks
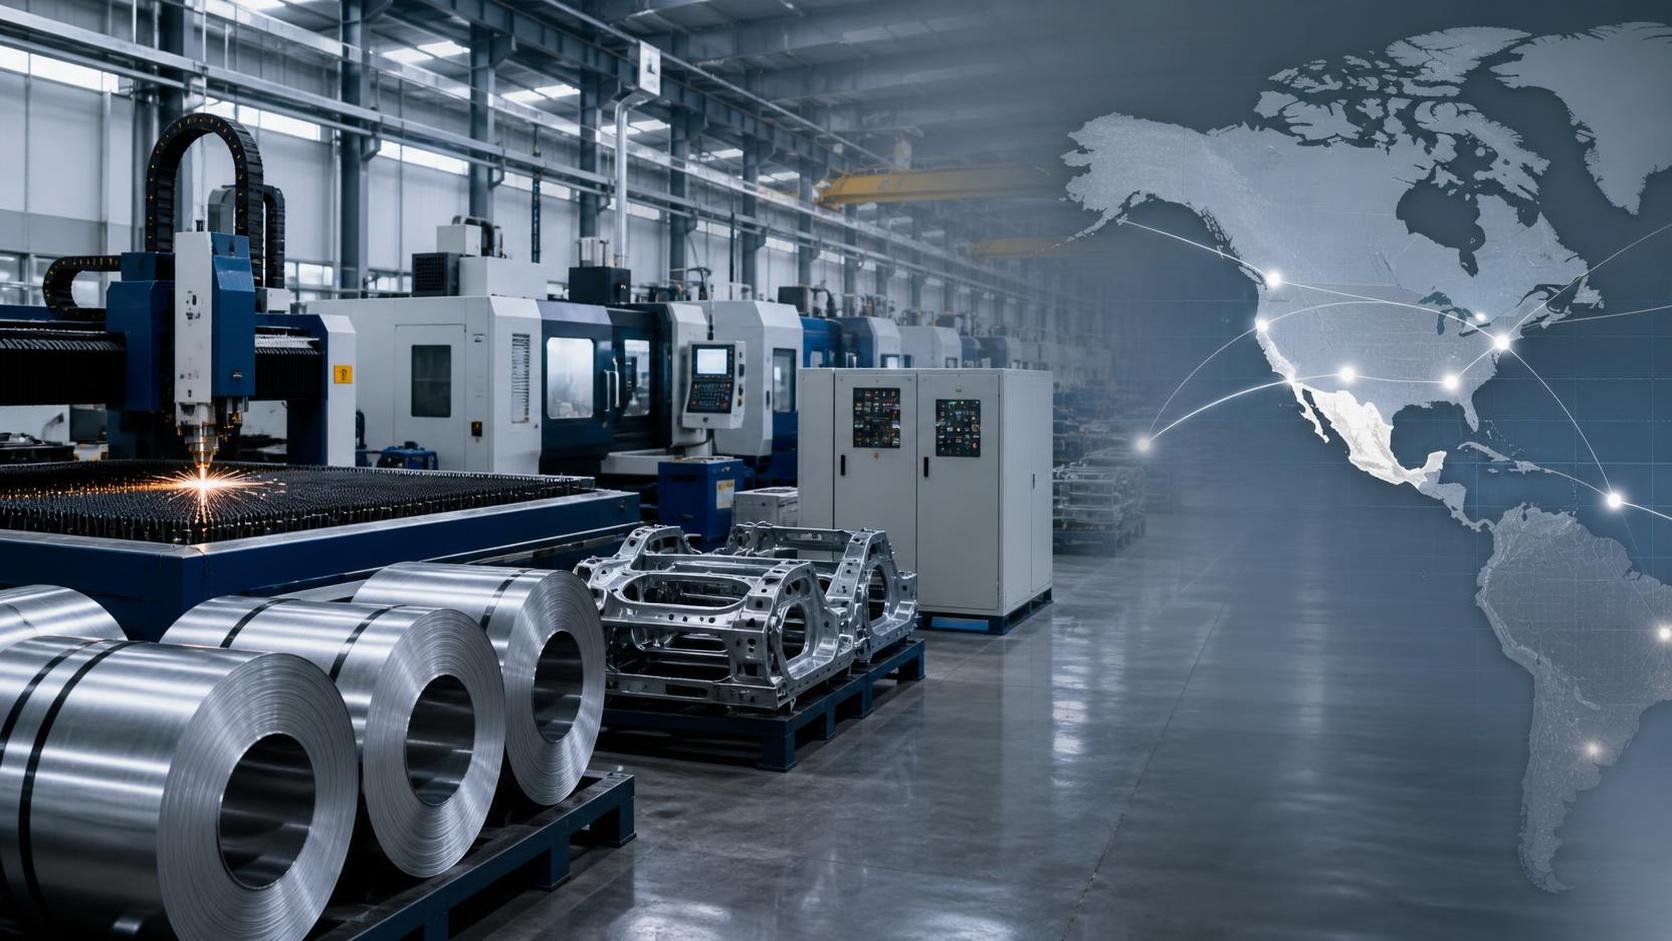
Mexico’s metal processing industry is no longer just a supporting layer beneath North American manufacturing. It is increasingly part of the strategic conversation around regionalization, industrial resilience, and cost-risk balance. For companies evaluating suppliers, market entry, or investment targets, the question is not simply whether demand is growing. The more useful question is where growth is concentrating, what is driving it, and which risks could quietly erode margins or delivery reliability.
That matters because the metal processing industry in Mexico sits at the intersection of several demanding sectors: automotive, appliances, construction products, electrical equipment, machinery, and increasingly the infrastructure needed for energy and logistics. These downstream markets do not buy “metal processing” in the abstract. They buy stamped parts, machined components, welded assemblies, castings, coils, structural products, enclosures, brackets, tubes, and precision subassemblies that must meet lead-time, tolerance, traceability, and compliance expectations.
Mexico has some clear advantages in that environment: proximity to the United States, a deep manufacturing base, established industrial corridors, and a workforce experienced in export-oriented production. But those strengths do not remove the operational risks. In fact, as procurement shifts from single-country sourcing toward “nearshoring” or dual-sourcing models, the pressure on local metalworking capacity, power reliability, labor availability, and logistics coordination tends to rise.
Where demand is coming from
Automotive remains the most visible demand engine. Mexico’s role in vehicle production and parts manufacturing supports a wide range of processing activities, from stamping and roll forming to CNC machining, die casting, heat treatment, and welded fabrication. Even when final vehicle demand moves in cycles, the supply chain often continues to require tooling upgrades, replacement components, localized sourcing, and process transfers from other regions. For evaluators, that means capacity may look available on paper while in reality being tied up by long-term automotive programs with strict quality and PPAP-style requirements.
Appliances are another important pillar. Mexico has long been a manufacturing base for refrigerators, cooking equipment, HVAC-related products, and white goods serving both domestic and export markets. This creates steady demand for coated sheet metal, housings, brackets, fasteners, tubes, wire forms, and electrical-mechanical assemblies. Compared with automotive, appliance work may allow more flexibility in some categories, but it still depends heavily on cost control and repeatable throughput.
Construction-linked processing is more mixed. It includes structural steel, rebar-related fabrication, roofing and cladding products, doors, frames, industrial racks, utility enclosures, and components used in commercial or infrastructure projects. Growth here is often tied to industrial park development, warehousing, transport infrastructure, and public or private capital spending rather than one single national trend. Business evaluation teams should be careful not to treat “construction demand” as one homogeneous market. The risk profile for export-oriented fabricated enclosures is very different from that of locally supplied structural products.
Machinery and industrial equipment are also worth watching. As more production is localized in Mexico, there is usually a parallel increase in demand for machine frames, guards, conveyors, skids, housings, electrical cabinets, brackets, shafts, and precision mechanical parts. This is where the metal processing industry in Mexico connects directly with the broader industrial ecosystem tracked by platforms such as NEXUSINSIGHTS, which follows manufacturing machinery, industrial equipment, mechanical components, electrical systems, and cross-border supply chain developments. For companies trying to read market direction, that broader context matters more than a narrow view of one product category.
Why nearshoring helps—but also complicates supplier assessment
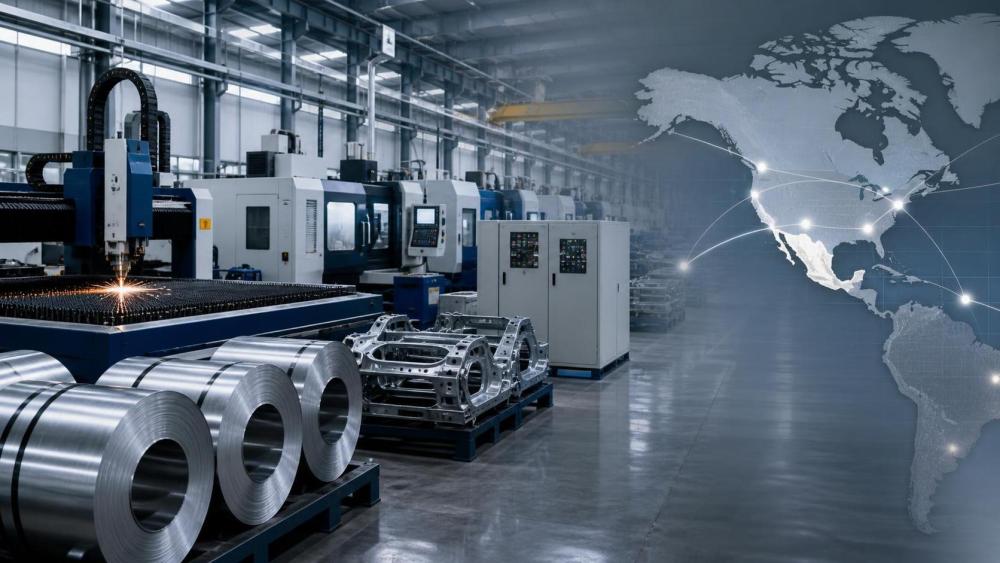
Nearshoring has supported Mexico’s industrial narrative, but the term is often used too loosely. In metal processing, nearshoring does not automatically mean abundant capacity, lower risk, or faster onboarding. A buyer moving work from Asia to Mexico may gain shorter transit times and easier engineering communication with North American teams, yet still face bottlenecks in tooling, finishing, high-precision machining, or material conversion.
One common mistake is to evaluate suppliers mainly by geography. A plant in northern Mexico may appear ideal because it reduces border transit time, but location alone says little about scrap control, preventive maintenance discipline, die capability, secondary operations management, or whether key inputs are imported with long replenishment cycles. Another supplier deeper in the country may actually be more resilient if it has diversified mills, stronger process controls, and more stable utility arrangements.
This is also where business intelligence becomes practical rather than theoretical. Monitoring company expansions, equipment investments, industrial park development, policy shifts, and export patterns can reveal whether a supplier base is genuinely scaling or simply absorbing demand until lead times stretch. That type of signal tracking is one reason decision-makers use industry information platforms rather than relying only on supplier presentations.
The supply chain risks that deserve closer scrutiny
Raw material exposure is still the first issue to test. Many Mexican processors work with steel, aluminum, stainless, copper, or specialty alloys whose pricing and availability are shaped by global dynamics, not only local demand. Even when a supplier quotes in stable terms, the hidden question is whether it has secured sourcing from domestic mills, U.S. service centers, imports, or a mix of all three. The answer affects lead times, pricing flexibility, and vulnerability to transport or customs delays.
Energy is another risk that can be underestimated by non-operators. Metal processing is power-intensive, and electricity quality matters as much as electricity cost in certain processes. Machining centers, welding lines, heat treatment equipment, laser cutting systems, and coating operations all depend on stable utilities. In some regions, site-specific constraints related to grid access, power quality, or future expansion capacity may shape what a supplier can realistically deliver. For a buyer, this is not an abstract infrastructure discussion; it can become a late-stage production bottleneck.
Logistics sounds straightforward until the supply chain is under pressure. Cross-border freight from Mexico to the U.S. can be efficient, but efficiency depends on lane conditions, carrier availability, border congestion, documentation accuracy, and the packaging discipline needed to protect fabricated or machined parts. Bulky, high-mix, or surface-sensitive products create additional complexity. It is worth checking whether suppliers manage export documentation directly, rely on third-party operators, or only ship within domestic Mexico and leave border coordination to the customer.
Trade policy risk should also stay on the table. For many industrial buyers, Mexico’s appeal is tied to North American trade integration. But policy interpretation, customs treatment, rules-of-origin compliance, and product-specific duties can still affect project economics. This is especially relevant when metal inputs or intermediate components come from outside the region before final transformation in Mexico. A sourcing decision that looks efficient at the quotation stage may become less attractive once tariff classification and origin requirements are fully reviewed.
A practical risk lens for evaluation teams
Regional concentration matters more than many buyers expect
The Mexican market is not one single operating environment. Northern states linked to cross-border manufacturing often offer logistics advantages and mature supplier ecosystems, especially for automotive and export assembly. Central regions may provide different mixes of labor, customer concentration, and industrial capabilities. Bajío remains highly relevant for automotive and advanced manufacturing networks. In practice, supplier evaluation usually works best when mapped by corridor, not by country-level assumptions.
This affects costs in subtle ways. A plant can be competitive on conversion cost but weak on inbound material freight. Another may be well equipped yet face labor churn because of local competition for skilled machinists, maintenance technicians, or welders. The result is that “Mexico sourcing” can mean very different operating realities depending on region, product complexity, and export path.
What separates stronger suppliers from merely available ones
In the current market, many suppliers can say yes to RFQs. Fewer can absorb engineering changes, hold consistent quality through volume ramps, and manage secondary processes without lead-time drift. In metal processing, resilience often shows up in ordinary details: how dies are maintained, whether scrap trends are tracked at shift level, how surface defects are isolated, whether subcontracted finishing is audited, and how quickly replacement tooling can be sourced.
For business evaluation teams, it helps to separate capacity from capability. A shop may have open machine hours but limited fixturing expertise. A fabricator may be strong in cutting and bending but rely on fragile outsourcing for coating or heat treatment. A plant with modern equipment may still struggle if planning systems, operator training, or spare parts availability are weak. These are not unusual problems; they are common transition risks when demand grows faster than industrial support systems.
This is where ongoing market tracking has value. NEXUSINSIGHTS, for example, is useful not because it promises a single answer, but because industrial buyers often need a wider field of view: machinery upgrades, supplier expansions, automation trends, policy developments, exhibition activity, and shifts in export manufacturing. Those signals help teams judge whether a metal processor is positioned inside a strengthening ecosystem or operating at its edge.
How to read the market over the next few years
The broad direction still favors Mexico, especially where customer requirements align with North American delivery windows, engineering coordination, and trade-zone advantages. Automotive transition programs, appliance manufacturing, industrial equipment localization, warehouse and infrastructure build-out, and electrical enclosure demand should continue to support metal conversion and fabrication activity.
Still, growth is unlikely to be smooth. Margin pressure from raw materials, regional utility constraints, labor competition, and cross-border logistics volatility will continue to separate well-managed suppliers from weaker ones. Evaluators should be cautious with assumptions that every nearshoring-driven segment will scale at the same pace. In reality, higher-complexity work often depends on tooling, process validation, and supporting services that take time to build.
A sensible next step is not to ask whether the metal processing industry in Mexico is attractive in general. It is to narrow the question: which product family, which region, which process chain, which material exposure, and which delivery model fit your requirements. Once those variables are clear, market intelligence becomes much more actionable, and supply chain risk becomes easier to price rather than simply worry about.
That is ultimately the real opportunity in Mexico today: not generic optimism, but sharper selection.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.