
Energy Industry News: Early Signals of Supply Tightening


Energy industry news is sending early signals of supply tightening, a trend that procurement professionals cannot afford to overlook. From shifting fuel availability and equipment lead times to policy changes and logistics pressure, these developments are beginning to reshape sourcing costs and planning decisions. This article highlights the key market indicators behind the current outlook and what buyers in industrial and electrical supply chains should watch next.
Why is energy industry news suddenly getting so much attention from procurement teams?
For many buyers, energy industry news used to be something monitored mainly by utilities, oil traders, or large commodity desks. That has changed. Today, procurement teams in manufacturing, industrial equipment, electrical components, and processing machinery are paying close attention because energy conditions now affect much more than fuel bills. They influence raw material pricing, factory operating costs, freight rates, supplier capacity, and even the availability of critical equipment such as transformers, switchgear, motors, cables, generators, and control systems.
When supply tightening begins, the earliest impact is often indirect. A plant may still be operating, but it could face higher power costs, constrained natural gas access, or delayed maintenance shutdowns. Those pressures then move into quotations, contract terms, and lead times. By the time shortages become obvious in public headlines, buyers are often already dealing with price revisions and weakened delivery reliability.
This is why current energy industry news matters to procurement professionals. It serves as an early warning system. If energy-intensive producers start signaling higher costs, if grid upgrades lag demand growth, or if fuel inventories tighten ahead of peak season, sourcing managers can expect ripple effects across industrial and electrical supply chains.
What does “early signals of supply tightening” actually mean in practical sourcing terms?
In practical terms, supply tightening does not always mean an immediate shortage. It usually means the market is losing flexibility. There is less buffer in fuel inventories, less spare production capacity at upstream plants, less room in transport networks, and less tolerance for disruptions caused by weather, policy shifts, maintenance, or geopolitics. Procurement teams should interpret this as a rising probability of cost volatility and a lower margin for planning mistakes.
Several signs often appear together. Suppliers may shorten quotation validity periods. Manufacturers may become less willing to hold prices for future deliveries. Energy-linked surcharges may return in logistics and production contracts. Lead times for electrical and industrial equipment may become less predictable, especially where copper, aluminum, steel, resins, or specialty electronic parts are involved.
Another important point is that tightening can happen unevenly. One fuel segment may remain stable while power infrastructure components become constrained. One region may have adequate generation capacity while another faces grid congestion or weather-related transmission risk. Good procurement practice means reading energy industry news not as a single trend, but as a layered set of regional and product-specific signals.
Which indicators in energy industry news should buyers monitor first?
Not every headline deserves the same weight. Procurement professionals should focus on indicators that connect directly to purchase cost, lead time, and supply continuity. The first is fuel availability, especially natural gas, coal, refined products, and power generation inputs that can influence industrial operating costs. If producers face tighter fuel economics, the cost pressure can spread quickly into metals processing, component manufacturing, and logistics.
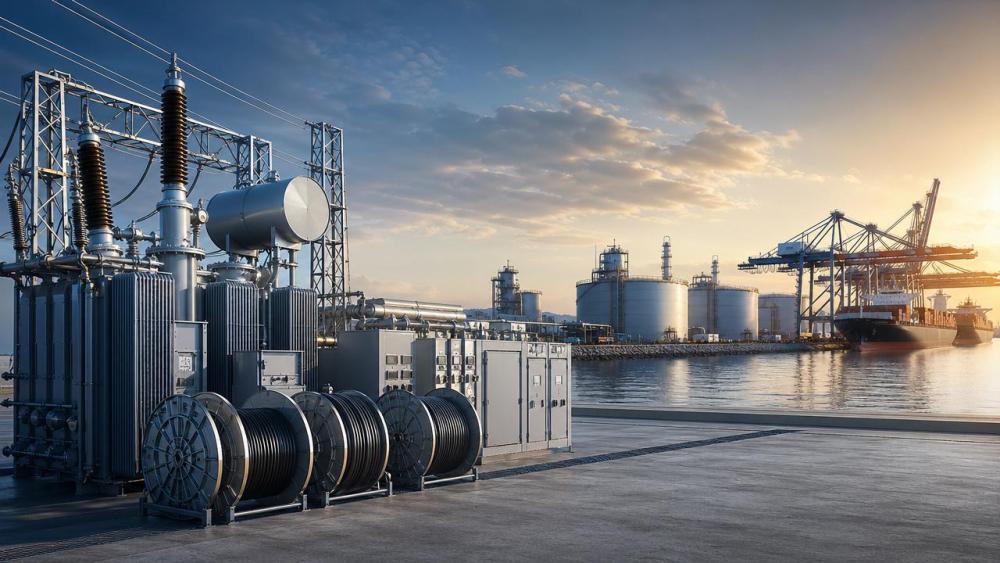
The second indicator is equipment lead time. In many cases, energy industry news about grid expansion, renewable integration, backup generation, and substation investment points to rising demand for the same electrical products used by industrial buyers. When utilities, EPC contractors, and large infrastructure projects compete for transformers, breakers, cable systems, and control hardware, smaller or mid-sized buyers may find availability reduced.
The third indicator is policy direction. Carbon regulation, fuel export controls, industrial subsidies, grid modernization plans, and emergency energy measures can all change supplier behavior. A policy that looks positive in the long term may still create short-term bottlenecks if it accelerates demand faster than manufacturing capacity can respond.
Fourth, buyers should track logistics conditions. Energy supply chains depend on ports, rail, pipelines, and heavy-haul transport. Disruptions in one part of that network can delay both fuel and equipment. In current energy industry news, transport and infrastructure constraints often reveal themselves before price spikes become severe.
How could supply tightening affect manufacturing, industrial equipment, and electrical procurement?
The effects usually show up in four areas: pricing, lead times, supplier willingness, and planning complexity. On pricing, energy-intensive products are the most exposed. Steel parts, castings, aluminum components, wire and cable, insulation materials, and some electronics can all become more expensive when energy costs rise or upstream availability tightens. Even if the product itself is not energy-related, the supplier’s production economics may be.
On lead times, electrical equipment is especially vulnerable because demand is being pulled by multiple sectors at once: utilities, industrial automation projects, data infrastructure, renewable installations, and plant upgrades. Procurement teams sourcing motors, drives, switchboards, connectors, batteries, or power distribution assemblies should watch whether suppliers are signaling allocation, revised schedules, or changes in minimum order expectations.
Supplier willingness is another underappreciated factor. In a tightening market, suppliers often become selective. They may prioritize larger accounts, standard specifications, or customers with stronger forecasting discipline. Buyers who rely on spot purchases, late-stage design changes, or fragmented order planning may face worse service levels than expected.
Finally, planning becomes harder. Forecast error costs more in a tighter market. Underbuying can lead to production risk, while overbuying can create cash pressure and inventory imbalance. That is why procurement teams need to integrate energy industry news into broader supply chain intelligence rather than treating it as a separate market category.
What are the most common misreadings of energy industry news?
One common mistake is assuming that stable spot prices mean supply is comfortable. Spot pricing can remain calm for a period even when inventories are thinning or lead times are worsening. Buyers who wait for dramatic price moves may react too late. The better approach is to combine price data with capacity utilization, maintenance schedules, delivery performance, and policy developments.
A second mistake is focusing only on fuels and ignoring equipment bottlenecks. In many industrial purchasing scenarios, the biggest risk is not a direct shortage of energy, but delayed access to the products needed to use, distribute, convert, or control energy. A transformer delay, cable shortage, or switchgear bottleneck can slow an entire expansion or replacement plan.
A third mistake is treating all regions the same. Energy industry news is highly location-sensitive. Grid reliability, policy enforcement, import dependence, local manufacturing capacity, and transport infrastructure vary widely. Procurement teams with cross-border sourcing responsibilities should compare local exposure rather than relying on broad global headlines.
The fourth mistake is assuming that suppliers will absorb cost shocks. In a soft market, suppliers may protect relationships by delaying price increases. In a tightening market, they are more likely to pass through higher energy, freight, and material costs quickly. Contract language, formula pricing, and change-notice procedures therefore matter more than usual.
How should procurement teams respond without overreacting?
The goal is not panic buying. It is disciplined preparation. First, segment your categories by exposure. Products linked to energy-intensive processing, imported electrical assemblies, or project-based supply should receive closer monitoring than low-risk, locally abundant items. A category-by-category view helps avoid broad actions that tie up capital unnecessarily.
Second, strengthen supplier communication. Ask about current lead times, surge capacity, raw material dependency, energy cost pass-through mechanisms, and logistics vulnerabilities. In a volatile environment, silence is a risk. Buyers often gain better outcomes simply by improving forecast transparency and order visibility.
Third, review specification flexibility. Where technically acceptable, alternative brands, equivalent grades, modular substitutions, or dual-sourcing options can reduce exposure. This is especially relevant in industrial equipment and electrical supplies, where a single constrained component can hold up a larger assembly.
Fourth, build timing buffers into projects. If energy industry news points to tighter market conditions over the next quarter or season, earlier release of long-lead items may be wiser than trying to optimize every purchase to the last minute. The cost of expedited recovery is often much higher than the cost of moderate schedule protection.
Quick response checklist for buyers
What should buyers confirm before making sourcing or inventory decisions?
Before increasing order volume or adjusting safety stock, buyers should confirm whether the warning signs in energy industry news are temporary, regional, or structural. Temporary issues may justify tactical buffers. Structural tightening may require broader sourcing redesign, new supplier qualification, or contract renegotiation. Without this distinction, companies risk either overbuying or reacting too slowly.
It is also important to confirm where the real bottleneck sits. Is the issue fuel availability, a utility constraint, a manufacturing capacity limit, a shortage of electrical components, or outbound logistics? Different causes require different responses. For example, a freight bottleneck may be managed with route diversification, while a transformer capacity shortage may require early commitment and technical standardization.
Procurement leaders should also compare supplier statements with external signals. If a vendor reports stable conditions but public energy industry news shows tightening inventories, policy disruption, or infrastructure strain, the prudent step is further validation. Independent market analysis, trade data, exhibition intelligence, and supply chain monitoring can help buyers cross-check assumptions.
Finally, confirm internal readiness. Can engineering approve substitutes quickly? Can finance support earlier purchasing if needed? Can operations provide better demand visibility? Supply tightening is rarely solved by procurement alone. It requires coordination across technical, commercial, and planning functions.
What is the practical takeaway from current energy industry news?
The main takeaway is that early supply tightening signals should be treated as a decision input, not as background noise. For procurement professionals, the value of energy industry news lies in its ability to reveal cost pressure, availability risk, and project timing exposure before those issues become urgent. Buyers in manufacturing, industrial equipment, and electrical supply chains should not wait for a full-blown shortage to start asking better questions.
A practical response begins with sharper monitoring, better supplier dialogue, and clearer category prioritization. It also requires attention to contracts, alternatives, project sequencing, and regional risk differences. Markets do not need to collapse to become harder to buy from; they only need to lose flexibility. That is often what the latest energy industry news is really signaling.
If you need to confirm a more specific sourcing plan, pricing direction, lead-time outlook, technical alternative, or supplier cooperation approach, the first questions to discuss should be these: which categories are most exposed, how long current quotations remain valid, where substitution is possible, what delivery risks are rising by region, and how much schedule buffer is realistic for the next procurement cycle.
 Steam Turbine Generator Packages: Defining Supply ScopeTime : Nov 09, 2026
 Choosing Portable Generators for Home Backup: Wattage and Fuel OptionsTime : Nov 07, 2026
- Oil Refining Market in India: Capacity, Demand and Growth DriversTime : Nov 05, 2026

Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.