Excavator industry news: is inventory pressure easing at last?

After months of oversupply and cautious buying, the latest excavator industry news suggests inventory pressure may finally be easing. Against a backdrop of heavy machinery market updates, construction equipment market shifts, and broader construction machinery news, buyers and decision-makers are watching whether demand recovery, dealer destocking, and project activity can truly support a more balanced market.
For information researchers, equipment users, procurement teams, and business leaders, the key issue is not whether the market has fully recovered, but whether inventory conditions are moving from disorder to discipline. That distinction matters because excavator inventory affects pricing power, lead times, financing terms, aftermarket support, and the timing of replacement or fleet expansion decisions across manufacturing, industrial equipment, and supply chain channels.
Recent market signals point to a more selective rebound rather than a broad-based surge. Small and medium excavators linked to municipal work, utilities, landscaping, and compact construction may clear faster than large mining or heavy earthmoving units. At the same time, dealers are becoming more cautious about stock depth, often targeting 1.5-3 months of sellable inventory instead of the 4-6 months seen during peak oversupply periods.
That shift creates both opportunities and risks. Buyers may gain stronger negotiation leverage in the short term, but waiting too long can mean losing access to preferred configurations, hydraulic attachments, or delivery windows when project starts accelerate. Understanding where inventory pressure is easing, and where it remains high, is now central to practical purchasing and market analysis.
What is really changing in the excavator inventory cycle?
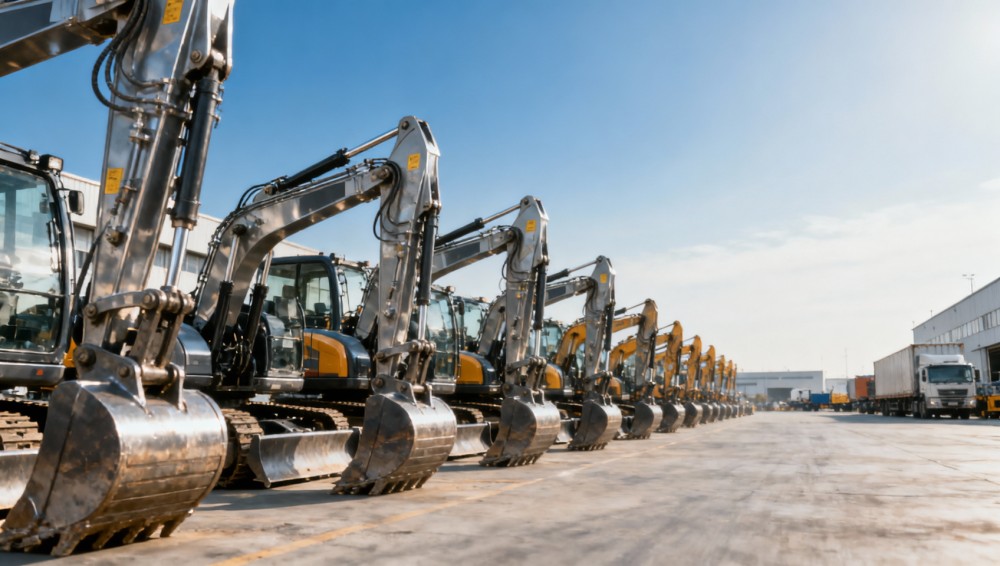
The most important change in current excavator industry news is that inventory pressure appears to be shifting from accumulation to controlled digestion. This does not mean the market is tight. It means the pace of dealer destocking, project bidding, and replacement demand is becoming more aligned than it was 2-3 quarters ago. In practical terms, fewer distributors want to hold aged units for longer than 120-180 days.
In many markets, oversupply was driven by three overlapping factors: aggressive production planning, softer-than-expected construction starts, and buyer hesitation caused by financing costs. Even if orders stabilize, a real easing of pressure only happens when monthly sell-through exceeds new arrivals for a sustained period, often for 8-12 weeks. That is why isolated sales spikes should not be mistaken for a full market reset.
Another visible change is product mix. Compact and 6-15 ton classes often move more quickly because they serve road maintenance, urban projects, rental fleets, and light industrial works. By contrast, 20-40 ton machines can face longer holding periods if large infrastructure or quarry activity remains uneven. This segmentation is one reason overall inventory headlines can hide very different realities by machine size.
Signals that easing is genuine rather than temporary
Decision-makers should watch four practical indicators instead of relying on sentiment alone. First, average stock age should decline quarter over quarter. Second, discounting should narrow from distressed clearance levels to more normal promotional ranges. Third, spare parts demand should improve with machine utilization. Fourth, rental conversion and trade-in activity should rise, which usually indicates better confidence among contractors and fleet managers.
Key market checkpoints
- Dealer inventory aging: below 90 days is healthier than 120-180 day stock.
- Stock-to-sales ratio: a move from around 4:1 toward 2:1 often signals better balance.
- Promotion intensity: lower cash rebates and fewer bundled giveaways suggest reduced pressure.
- Service workshop utilization: increased maintenance bookings often track with higher field activity.
The table below summarizes the main signals buyers and channel partners can use to judge whether excavator inventory pressure is truly easing, remaining flat, or merely being masked by temporary discounts.
The critical conclusion is that inventory relief should be measured through operating data, not headlines alone. If stock age, sell-through, and service utilization improve together, the excavator market is likely moving into a healthier phase. If only discounts increase, pressure may simply be delayed rather than reduced.
Why inventory pressure matters to buyers, operators, and procurement teams
Inventory pressure shapes purchasing conditions far beyond the listed machine price. When dealers carry too much excavator stock, they may offer stronger financing support, free maintenance for the first 500-1,000 operating hours, or bundled attachments such as buckets, breakers, or quick couplers. For procurement managers, those extras can improve total acquisition value by 5%-12% even if the base quotation changes only slightly.
Operators and fleet users are affected differently. High inventory often means faster delivery, easier access to replacement parts, and more room to compare cabin layout, control response, hydraulic setup, and telematics options. However, it can also mean some units have been stored for extended periods. Before acceptance, teams should check battery condition, seal aging, tire or track state, fluid integrity, and electronic system diagnostics.
For business leaders, the wider issue is capital timing. Buying during a destocking phase can reduce upfront cost, but the lowest price is not always the lowest lifecycle cost. A machine acquired at a 7% discount may still become more expensive if fuel efficiency is weaker, resale value falls faster, or service response exceeds 48-72 hours during peak project periods. That is why serious buyers look at ownership cost over 3-5 years, not only initial purchase terms.
Common procurement impacts during the destocking phase
In the current construction equipment market, procurement teams are typically balancing at least four variables: price, lead time, machine suitability, and after-sales support. If inventory pressure is easing, lead times for popular models may stretch from immediate delivery to 2-6 weeks, especially when specific emission packages, track shoes, booms, or hydraulic line options are required. This is often the first operational sign that excess stock is no longer abundant.
Practical buyer checklist
- Confirm the manufacturing date and storage period of the machine.
- Request a pre-delivery inspection covering hydraulics, electronics, and undercarriage wear.
- Compare warranty terms in months and operating hours, such as 12 months or 2,000 hours.
- Evaluate parts response time, ideally within 24-48 hours for critical service items.
- Check whether bundled attachments match your actual work cycle and soil condition.
The table below can help procurement teams compare the practical implications of buying under high inventory pressure versus buying when the market is rebalancing.
For most B2B buyers, the best window is not necessarily the point of maximum inventory pressure. It is the stage when prices are still competitive, but channel conditions have stabilized enough to ensure consistent service, predictable delivery, and better fleet planning. That balance matters more than headline discounts.
Which market drivers are helping inventory ease?
Several drivers are working together to reduce pressure in the excavator market, although their strength varies by region and machine class. The first is project normalization. Even when large-scale construction remains uneven, smaller projects in utilities, municipal repair, drainage, renewable energy installation, and factory site improvement can absorb a meaningful share of compact and medium excavators. This broadens the demand base beyond major infrastructure alone.
The second driver is dealer discipline. After carrying excess stock for multiple quarters, many channel partners have tightened replenishment cycles. Instead of ordering speculative volume, they are using shorter forecasting windows of 30-60 days and prioritizing fast-moving configurations. This reduces the risk of repeating old inventory mistakes and supports a steadier market-clearing process.
The third driver is replacement demand. Some users delayed fleet renewal during uncertain periods, extending utilization of existing machines. Once maintenance costs rise beyond practical thresholds, replacement becomes less optional. For example, if a machine exceeds 8,000-10,000 operating hours and repair downtime increases, replacing it with a more efficient unit may make financial sense even without a strong macro rebound.
Demand segments that may improve first
Not all segments recover in the same order. Compact units often benefit first because they are easier to finance, cheaper to transport, and adaptable to multiple jobsites. Medium units follow when infrastructure and industrial civil works regain momentum. Larger machines usually need clearer visibility on quarry, mining, or major land development pipelines before volumes improve sustainably.
Likely early-support demand sources
- Urban utility trenching, pipe replacement, and drainage upgrades.
- Factory expansion, logistics park preparation, and warehouse foundation work.
- Rental fleet refresh cycles focused on versatile 6-15 ton machines.
- Attachment-driven applications such as breaking, grading, and material handling.
These drivers matter because they create a more diverse outlet for stock reduction. A market relying on only one project type remains fragile. A market supported by 4-5 application areas is more likely to sustain better sell-through and reduce the chance of another inventory build-up.
Even so, buyers should remain cautious. Easing inventory pressure does not automatically equal strong pricing power for manufacturers. If financing remains expensive, export flows slow, or raw material costs rise sharply within a 6-12 month horizon, stock pressure can return. This is why channel intelligence, order discipline, and parts availability remain core indicators in construction machinery news analysis.
How to plan procurement while the market is rebalancing
A rebalancing market rewards structured procurement rather than reactive purchasing. Buyers should begin by defining application needs clearly: digging depth, lifting demands, attachment use, jobsite access, operating hours per month, and fuel targets. A mismatch at this stage can erase any savings gained from lower market prices. For instance, choosing a larger unit than required can increase fuel and transport cost by 10%-20% with no productivity advantage in confined worksites.
The next step is supplier evaluation. In a market moving out of oversupply, not all offers are equal. Some are genuine value deals on current stock; others are attempts to clear slow-moving or overly customized machines. Procurement teams should request a written specification list, storage condition records where available, service network details, and delivery commitments that include parts support for at least the first 12 months.
A 5-step procurement framework
- Define workload and site conditions over the next 6-18 months.
- Shortlist 2-4 machine classes or configurations that fit the task profile.
- Compare lifecycle cost, including fuel, maintenance intervals, and resale potential.
- Audit after-sales capacity, technician response time, and critical spare parts availability.
- Negotiate not only price, but also delivery timing, training, attachments, and warranty scope.
For operators and end users, field validation is just as important as paperwork. A practical trial should review bucket response, travel stability, visibility, cabin ergonomics, noise level, and compatibility with planned attachments. Even a 30-60 minute operating test can reveal issues that specification sheets miss, especially in hydraulic smoothness and control feel.
Risk points to avoid
- Buying only on discount without checking machine storage age and configuration fit.
- Ignoring undercarriage, hoses, seals, and electrical checks on long-held stock units.
- Assuming every dealer can support 24-48 hour parts response in your project region.
- Choosing attachments as “free extras” when they are not matched to hydraulic flow or job needs.
When the market is between oversupply and normalization, the strongest buyers are those who combine timing with discipline. They secure commercial value without sacrificing machine suitability, service continuity, or future fleet flexibility. That is especially important for industrial buyers who must coordinate equipment purchases with production schedules, subcontractor demand, and broader supply chain planning.
FAQ: practical questions about current excavator industry news
Is now a good time to buy an excavator, or is it better to wait?
It depends on application urgency and machine class. If you need a standard stock unit and can secure a solid warranty, parts support, and a competitive package, buying during a rebalancing phase can be efficient. Waiting may save a small additional amount in some cases, but it can also narrow configuration choice and extend lead times from a few days to several weeks.
Which excavator segments usually clear inventory first?
Compact and lower mid-range machines often clear first because they serve more job types, from municipal work to light industrial construction. Units in the 6-15 ton range usually have broader appeal than specialized large machines tied to mining or heavy earthmoving. This makes them more responsive to modest demand improvement.
What should buyers inspect on inventory machines that have been stored for a while?
Priority checks include seals, hoses, fluid condition, batteries, electronics, undercarriage wear, corrosion points, and startup diagnostics. Ask for pre-delivery testing and, if possible, an operational demonstration. For stock units held beyond 6 months, these checks become even more important before final acceptance.
How long is a normal delivery cycle when inventory pressure eases?
For standard models, delivery may still be immediate to 2 weeks if stock is available. For preferred configurations or bundled attachments, 2-6 weeks is common in a healthier market. If custom hydraulic lines, special booms, or export documentation are involved, the cycle can extend further depending on supplier readiness.
What metrics matter most for enterprise decision-makers?
Focus on stock age, lead time, service coverage, parts response, expected utilization, and 3-5 year ownership cost. These indicators reveal more than headline discounts. For businesses operating multiple sites, service consistency and parts availability often matter as much as purchase price because downtime can quickly absorb any initial savings.
The latest excavator industry news points to a market that is improving in structure, not fully recovered in volume. Inventory pressure may indeed be easing, but the pace differs by machine class, application, and regional project flow. Buyers who track stock age, sell-through, delivery timing, and after-sales capability will make better decisions than those reacting only to temporary price promotions.
For researchers, operators, procurement teams, and executives across manufacturing and industrial equipment channels, the best approach is clear: evaluate demand signals carefully, compare lifecycle value instead of sticker price alone, and align purchases with realistic workload and service needs. If you want deeper market analysis, tailored sourcing support, or more industry updates on construction machinery, heavy equipment, and supply chain trends, contact us now to get a customized solution and learn more.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.