Which construction materials could gain from China–Middle East trade in 2026
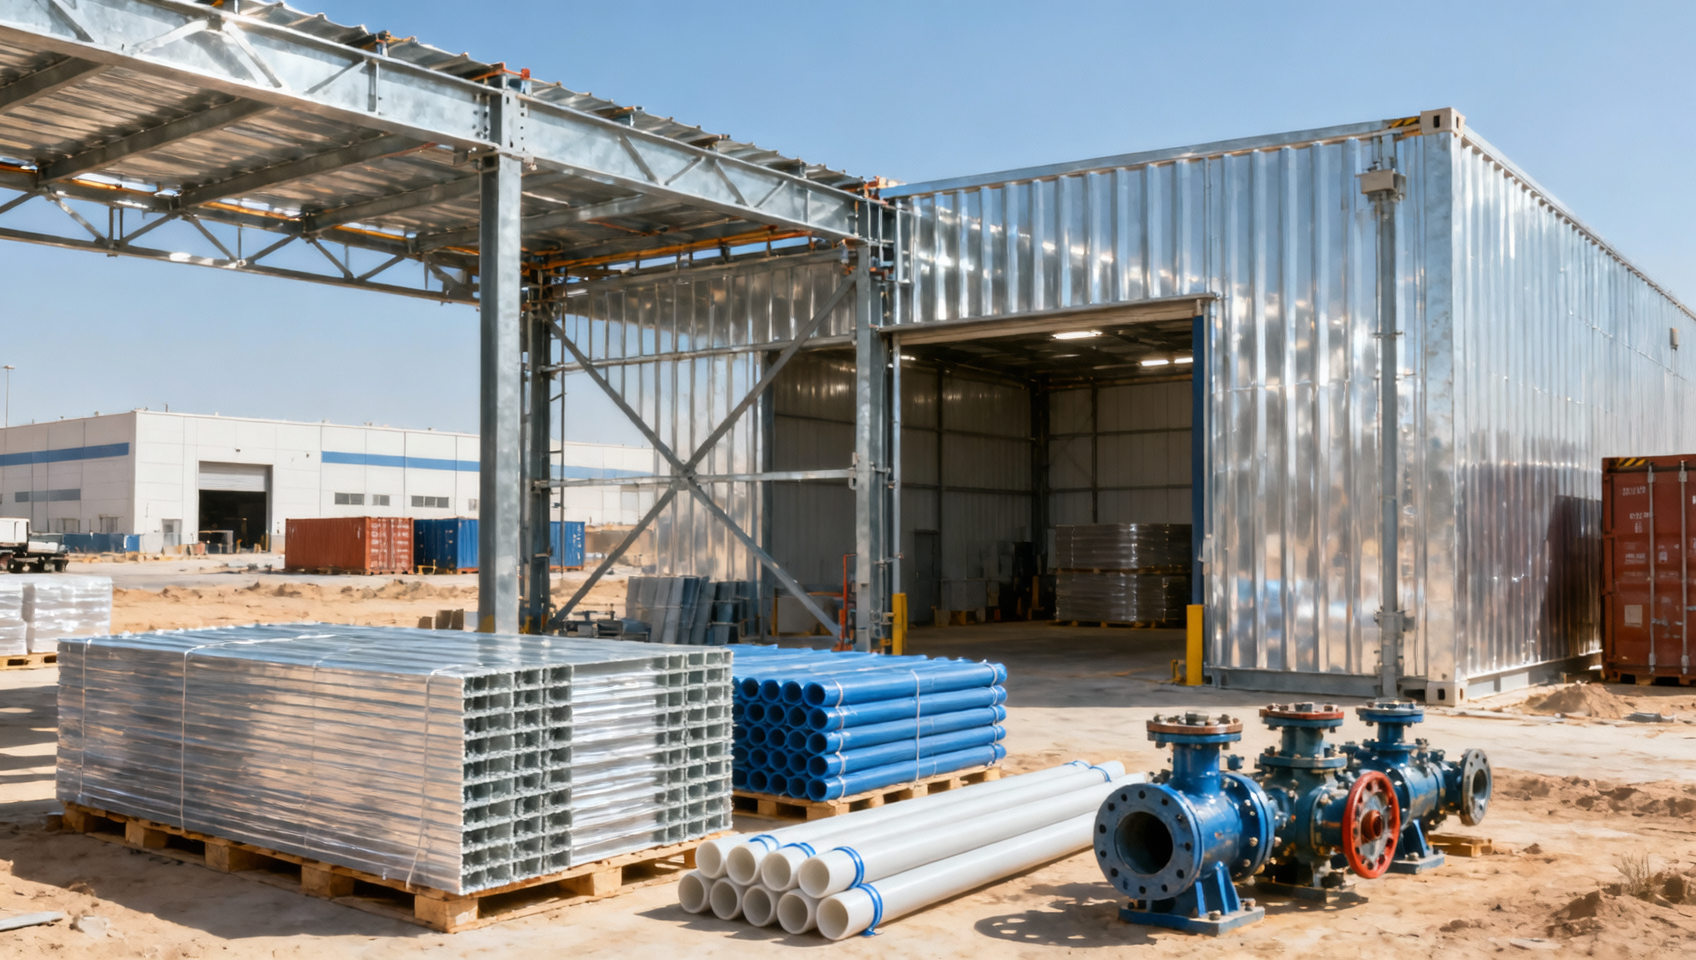
China–Middle East construction material trade export opportunities are likely to broaden in 2026, but distributors should prioritize technically specified, repeat-purchase categories instead of chasing every project tender.
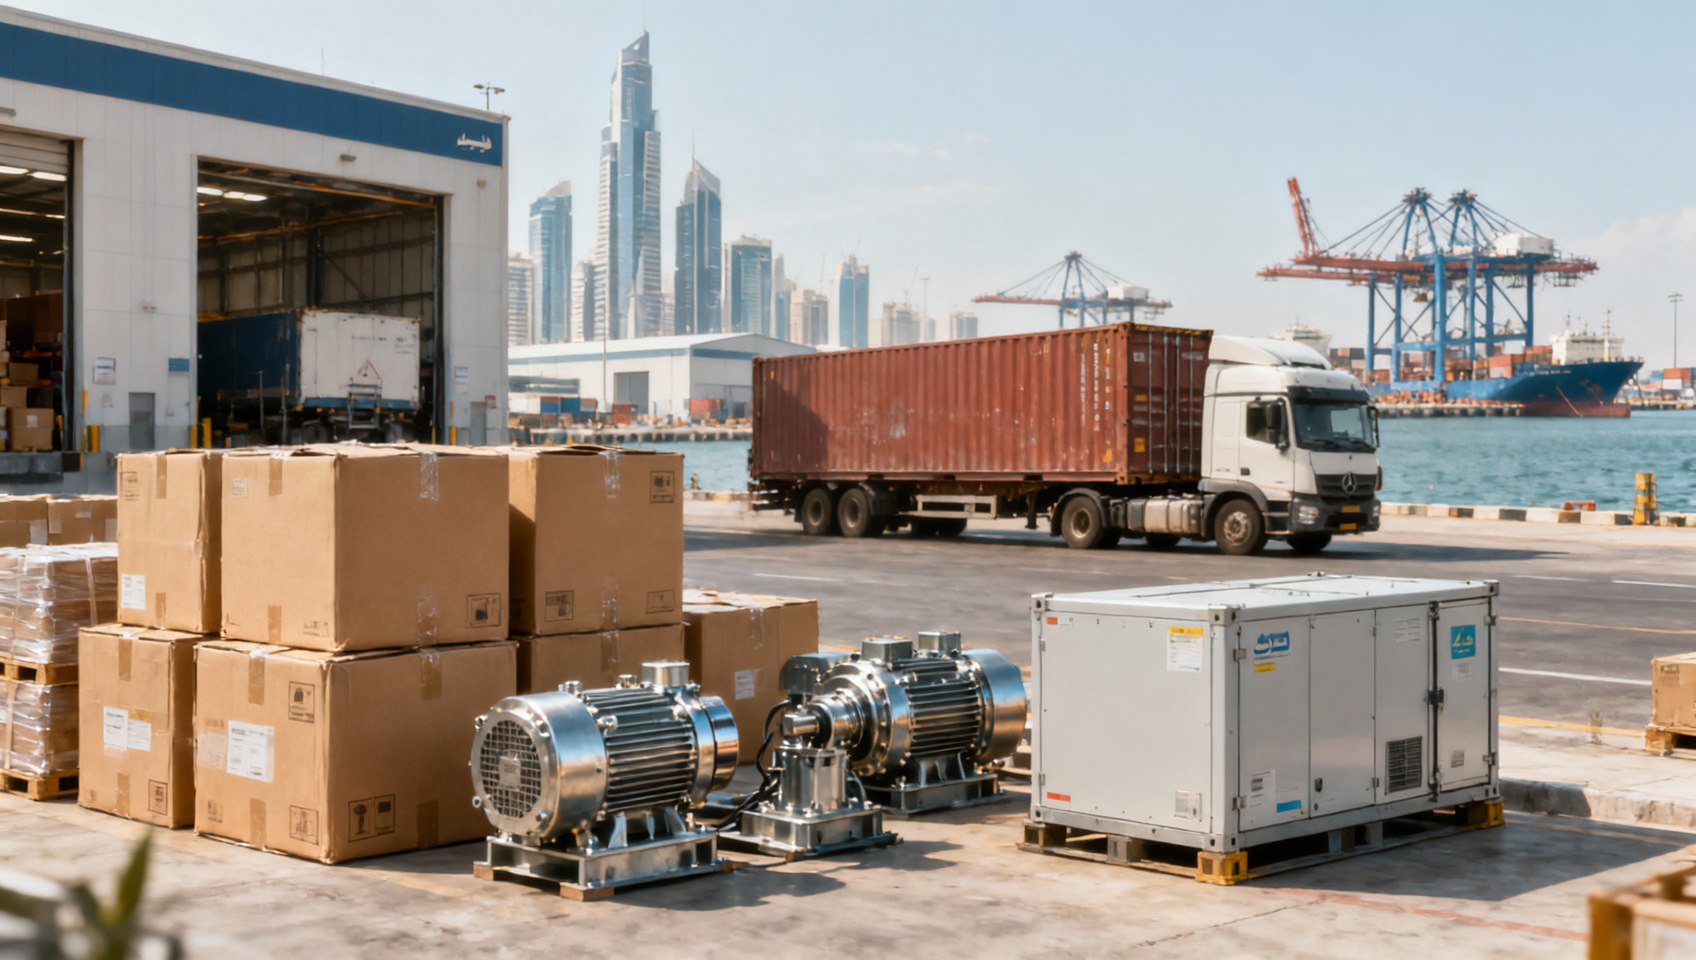
The strongest opportunities are expected in steel systems, pipes, insulation, architectural glass, modular products, and supporting equipment serving infrastructure, urban development, logistics, energy, and industrial facilities.
For distributors and agents, the commercial question is not simply which products China can supply cheaply, but which categories combine demand visibility, manageable compliance, local service needs, and sustainable margins.
Success will depend on choosing material lines that match each market's building codes, contractor relationships, warehousing capacity, payment practices, and project pipeline rather than relying on broad regional assumptions.
Why 2026 Could Favor Selected China–Middle East Construction Material Trade
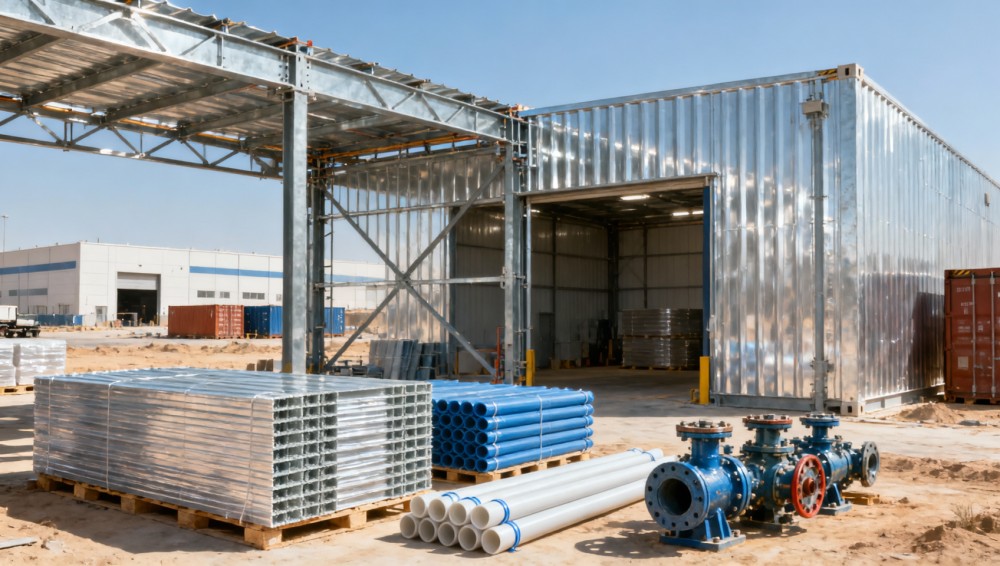
The Middle East remains a diverse group of markets, yet capital spending across Gulf states continues to support residential districts, transport corridors, industrial zones, utilities, tourism assets, and energy infrastructure.
Saudi Arabia, the United Arab Emirates, Qatar, Oman, Kuwait, and Bahrain have different procurement structures, but each requires reliable supply chains for construction, maintenance, expansion, and refurbishment projects.
Large headline projects attract attention, although distributors often find more dependable revenue in secondary packages, replacement demand, contractor stock requirements, and repeat orders from private developments.
Chinese suppliers can compete through manufacturing scale, broad product ranges, customization options, shorter development cycles, and increasingly mature export support for industrial and building-related goods.
However, price alone is becoming less decisive. Developers, EPC contractors, consultants, and authorities increasingly require tested systems, documented performance, traceability, approved samples, and dependable delivery commitments.
This changes the role of channel partners. A distributor that can translate specifications, hold fast-moving stock, coordinate certification, and resolve claims becomes more valuable than a simple trading intermediary.
China middle east construction material trade export growth in 2026 will therefore be uneven. Products that are easy to substitute may face aggressive pricing, while compliant systems can create better defensible margins.
Distributors should separate project-led demand from structural demand. Project-led demand can be substantial but irregular, whereas structural demand supports recurring sales through maintenance, fit-outs, logistics expansion, and local manufacturing.
A practical starting point is to identify materials with visible consumption drivers, realistic shipping economics, recognized standards, and a clear reason for customers to use a locally supported supplier.
Steel Products and Fabricated Systems Have Broadest Demand Potential
Steel is likely to remain one of the largest opportunity areas because it supports warehouses, factories, logistics parks, commercial buildings, infrastructure packages, renewable projects, and specialized industrial facilities.
Distributors should not treat steel as one market. Commodity rebar and basic sections can be intensely price-sensitive, while fabricated systems, coated products, and engineered components offer clearer differentiation.
Pre-engineered building structures are particularly relevant for industrial estates, storage facilities, workshops, agricultural buildings, aircraft hangars, and light manufacturing sites requiring faster construction schedules.
Chinese suppliers can provide structural frames, purlins, sandwich-panel interfaces, mezzanines, doors, roof systems, and accessories as coordinated packages rather than disconnected individual materials.
That package approach matters because contractors often need compatible components, predictable quantities, shop drawings, production control, and shipment sequencing that aligns with installation progress on site.
Galvanized steel products may also gain where corrosion resistance is essential. Coastal environments, humid conditions, water-related projects, and exterior applications increase demand for suitable coatings and controlled fabrication quality.
Agents should verify steel grades, coating weights, welding documentation, load calculations, fire requirements, and third-party inspection expectations before representing a supplier in a major project category.
Margins are often stronger in accessories and fabricated assemblies than in bulk tonnage. Fasteners, cable trays, fencing, grating, handrails, expansion joints, and custom brackets can create useful cross-selling opportunities.
The central risk is inventory exposure. Distributors should avoid holding too much specification-sensitive steel until they understand local approvals, customer consumption patterns, and the supplier's ability to replenish consistently.
Pipes, Valves, and Water Management Materials Offer Repeat-Sales Value
Water infrastructure is a durable demand driver across the region. Population growth, district expansion, irrigation, desalination, wastewater treatment, drainage, and cooling networks all require extensive pipe systems.
Potential categories include HDPE pipes, PVC and CPVC systems, ductile iron fittings, PPR products, drainage solutions, manholes, valves, pumps, filtration housings, and installation accessories.
For a distributor, pipe products are attractive when they generate repeat business from contractors, plumbers, facility managers, municipal suppliers, landscape firms, and maintenance companies beyond flagship projects.
Chinese manufacturers increasingly offer complete piping ranges, but local buyers will examine pressure ratings, raw material quality, joint reliability, dimensional consistency, certifications, and availability of compatible fittings.
Water-related products cannot be marketed successfully with generic catalogues alone. Sales teams need application knowledge covering potable water, irrigation, fire protection, sewage, industrial fluids, and chilled-water networks.
Fire protection lines deserve separate analysis because approval requirements can be strict. Agents should confirm accepted standards, listed components, inspection procedures, and whether project consultants recognize the proposed brand.
Storage matters in this category. Pipes can occupy large warehouse volumes, while fittings and valves require organized inventory management to avoid missed sales caused by one unavailable connecting component.
A profitable strategy may combine stocked, standard-diameter products with project-order systems. This limits working-capital pressure while still allowing the distributor to respond quickly to everyday customer requirements.
Insulation, Roofing, and Building Envelope Products Could Outperform Basic Materials
Energy efficiency requirements, extreme temperatures, cooling costs, and project operating-cost targets are increasing interest in insulation and building-envelope materials across many Middle Eastern construction segments.
Potential winners include rock wool, glass wool, PIR and PU sandwich panels, XPS boards, reflective insulation, waterproof membranes, roof coatings, sealants, cladding systems, and thermal break components.
These categories can offer better value than simple bulk materials because buyers assess performance, installation speed, fire behavior, lifecycle cost, and warranty support alongside initial purchase prices.
Sandwich panels are especially relevant for warehouses, cold stores, food-processing facilities, retail buildings, workshops, and modular structures where installation speed and thermal control influence project economics.
Cold-chain growth can support demand for insulated panels, refrigerated doors, floor insulation, vapor barriers, and temperature-control materials serving food distribution, pharmaceuticals, hospitality, and logistics operations.
Distributors should be cautious with fire-rated products. Test reports must correspond to the exact product construction, thickness, facing, core material, and intended assembly rather than a loosely similar sample.
Roofing opportunities also extend beyond new construction. Harsh weather, ultraviolet exposure, thermal movement, and maintenance needs create recurring demand for repair membranes, coatings, drainage components, and roof accessories.
Local technical support is a meaningful differentiator. Contractors need help with substrate preparation, installation conditions, detailing, compatibility, consumption rates, and warranty procedures when failures could be costly.
For channel partners, a limited but coherent envelope portfolio may be more effective than representing many unrelated brands. Compatible systems make technical selling easier and improve average order value.
Architectural Glass and Aluminum Systems Need a More Selective Approach
Architectural glass, aluminum profiles, curtain wall components, doors, windows, louvers, and façade accessories can benefit from ongoing commercial, hospitality, residential, and mixed-use development across major cities.
Yet this market rewards specialization. Products must meet demanding requirements for safety, thermal performance, acoustic control, wind loading, appearance consistency, and installation precision.
Chinese suppliers have strong capabilities in float glass, processed glass, coated glass, hardware, aluminum extrusion, and façade fabrication, but specification acceptance should be confirmed before commercial commitments.
Distributors may find practical openings in supporting categories, including glass hardware, sealants, gaskets, spacers, thermal-break strips, access panels, sun-shading products, and repair or replacement supplies.
These lines can be easier to stock and less dependent on winning a single large façade package. They also support relationships with fabricators, installers, maintenance contractors, and fit-out companies.
For larger systems, agents should assess whether their supplier can provide engineering calculations, detailed drawings, mock-up support, quality records, and site coordination when requested by consultants.
Long lead times and breakage risk require disciplined logistics planning. Glass shipments need appropriate packaging, insurance, inspection protocols, and clear responsibility for damage discovered after delivery.
A distributor should avoid promising façade performance independently. The contract must define design responsibility, installation responsibility, warranty boundaries, testing obligations, and the documentation supplied by each party.
Modular Construction Materials Could Gain Where Speed Is More Valuable Than Lowest Cost
Modular and prefabricated building materials may gain traction in 2026 as developers seek faster delivery for worker accommodation, hospitality units, clinics, schools, site offices, retail spaces, and remote facilities.
Relevant exports include light-gauge steel framing, modular bathrooms, insulated wall panels, prefabricated MEP assemblies, containerized rooms, raised floors, partition systems, and compact utility modules.
China's advantage is often factory integration. Suppliers can coordinate components, finishes, electrical systems, plumbing, fixtures, and packaging, reducing the number of separate procurement relationships required.
However, modular exports require early design alignment. Dimensions, transport restrictions, local assembly methods, fire rules, electrical standards, and utility connections should be reviewed before production begins.
Distributors should focus on products that can be locally assembled, adapted, repaired, and serviced. Fully imported finished modules may face costly logistics or regulatory barriers in certain applications.
The strongest commercial model may involve importing standardized components while partnering with local installers or fabricators for final assembly, customization, commissioning, and after-sales support.
This approach gives agents more control over service revenue and customer relationships. It also reduces concern among buyers who want local accountability for installation defects or future modifications.
How Distributors Should Screen Chinese Suppliers Before Entering 2026 Opportunities
Before adding a construction material line, distributors should test the opportunity against four questions: Is demand recurring, is compliance achievable, can inventory be managed, and is technical support available?
Start with market mapping. Identify active contractors, consultants, developers, EPC firms, wholesalers, and installers in the target city, then determine which brands and standards currently dominate each category.
Next, request complete supplier evidence rather than a price sheet. Product data sheets, test reports, factory audits, quality manuals, export references, packaging details, and lead-time commitments are essential.
Certification review should involve local expertise. A report accepted in one country or project may not satisfy another authority, consultant, insurer, or government procurement requirement.
Commercial terms deserve equal attention. Clarify minimum order quantities, currency exposure, payment stages, mould ownership, exclusivity conditions, spare-part obligations, and procedures for defective or delayed shipments.
Distributors should also evaluate whether the supplier protects channel relationships. Direct contact with local end users, uncontrolled price quotations, or overlapping agencies can undermine long-term market development.
Begin with a pilot program where possible. A small stock order, selected contractor trial, sample installation, or limited territory launch provides practical evidence before substantial warehousing commitments are made.
Sales teams need more than brochures. Product training, comparison tools, installation guidance, and objection-handling support help distributors turn technical features into credible commercial value for customers.
Finally, track performance by product family rather than total revenue alone. Gross margin, inventory turns, customer concentration, claims frequency, quotation conversion, and payment collection reveal whether a line is genuinely scalable.
Where Channel Partners Should Place Their Bets
The most promising China–Middle East construction material trade export categories in 2026 are likely to be those connected to industrial construction, water systems, energy efficiency, logistics expansion, and fast-track projects.
Steel systems, piping products, insulation, roofing, selected façade components, and modular materials all have potential, but each requires different technical capabilities, working capital, customer networks, and compliance preparation.
Distributors should prioritize categories where local availability, product knowledge, and responsive service create an advantage that online sourcing or one-time direct imports cannot easily replace.
The right opportunity is not necessarily the largest market segment. It is the category where a channel partner can secure approved supply, protect margins, deliver reliably, and build repeat customer demand.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.