Emission Control Equipment News: 2026 Supply Risks and Lead Times
As 2026 approaches, buyers are watching environmental equipment news for emission control more closely as supply risks, longer lead times, and shifting regulations reshape sourcing decisions.
For procurement teams, understanding market signals early can reduce project delays, control costs, and secure reliable suppliers. This update highlights the key disruptions, regional trends, and purchasing insights that matter most.
What Procurement Teams Need to Know First About 2026
The core search intent behind environmental equipment news for emission control is practical, not academic. Buyers want to know whether equipment will be available on time, at what cost, and from which regions.
They are not simply looking for a market overview. They need early warning signals that affect budgeting, project schedules, compliance timelines, supplier selection, and contract terms for 2026 purchasing plans.
The overall judgment is clear: supply conditions for emission control equipment are improving in some standard categories, but risk remains elevated for engineered systems, critical components, and compliance-sensitive projects.
Lead times are unlikely to normalize evenly across all product groups. Standard filtration and handling products may stabilize faster, while catalytic systems, controls, specialty alloys, and custom assemblies may remain constrained.
For purchasing professionals, the biggest mistake in 2026 may be assuming that lower freight volatility means lower sourcing risk. The real challenge is shifting from logistics disruption to component, compliance, and supplier-capacity risk.
Why Lead Times May Stay Longer Than Buyers Expect
Many procurement teams expect lead times to ease after several years of disruption. However, emission control equipment involves more than fabrication capacity. It also depends on engineering reviews, regulatory specifications, and integrated component availability.
In many projects, the bottleneck is no longer only steel or transport. It is the availability of burners, fans, sensors, PLCs, refractory materials, catalyst media, and approved electrical components.
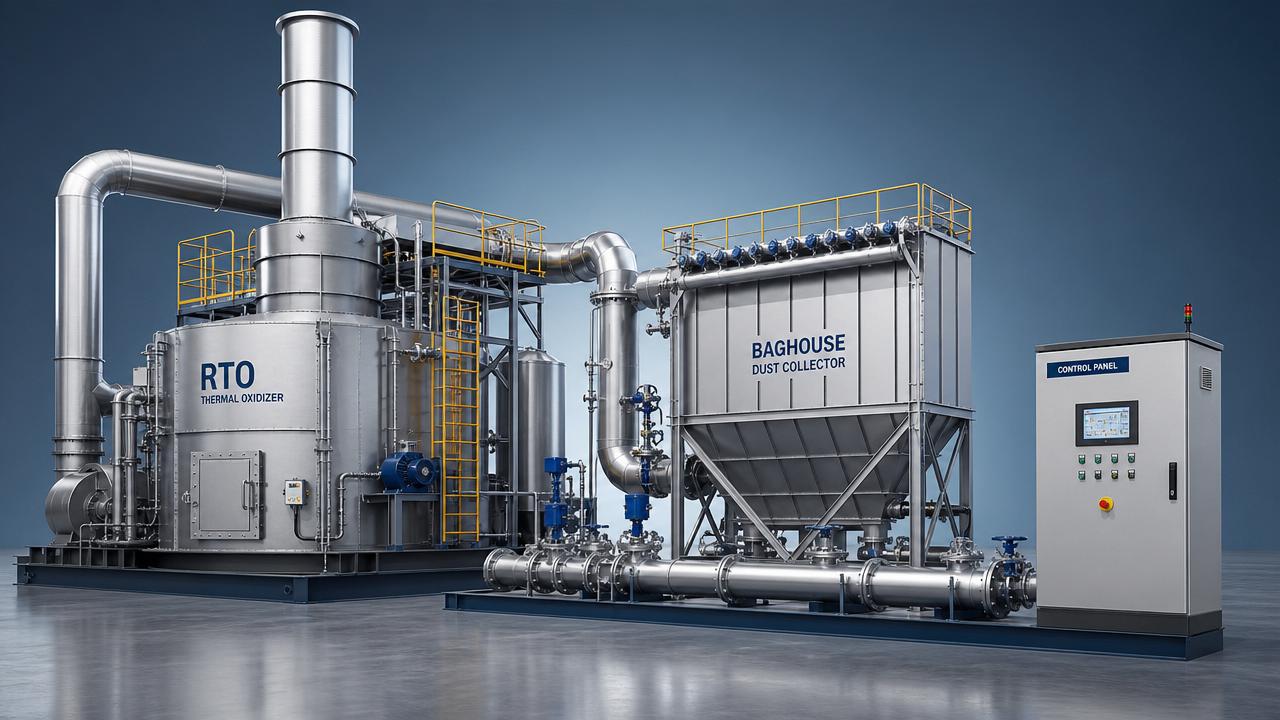
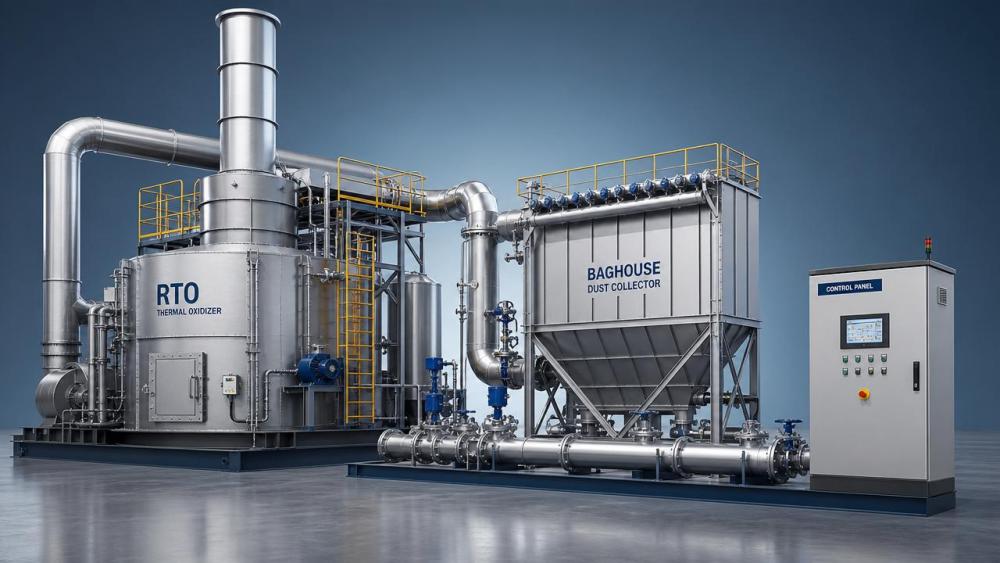
Custom systems such as thermal oxidizers, scrubbers, dust collectors, VOC treatment units, and flue gas cleaning packages often require supplier coordination across several tiers. A delay in one subsystem can move the entire delivery schedule.
Procurement teams should also account for longer approval cycles from end users, consultants, and local authorities. When technical revisions happen late, suppliers may lose reserved production slots and reset delivery dates.
Another factor is capacity allocation. Manufacturers serving both domestic and export markets may prioritize higher-margin, lower-risk contracts, especially when order books are full or compliance liabilities are high.
Which Product Categories Face the Highest Supply Risk
Not all emission control products carry the same risk profile. Buyers should separate routine replacement items from project-based engineered equipment and then assess exposure at the component level.
High-risk categories for 2026 are likely to include regenerative thermal oxidizers, selective catalytic reduction systems, activated carbon treatment units, advanced baghouse systems, industrial gas analyzers, and integrated control cabinets.
Projects involving high-temperature materials or corrosion-resistant construction may face additional pressure. Stainless steel grades, specialty coatings, ceramic internals, and imported valves can all extend lead times unexpectedly.
Catalyst-related products deserve special attention. Procurement exposure includes not only raw catalyst supply but also regeneration services, performance guarantees, reactor design compatibility, and transport restrictions in some regions.
Spare parts can also become a hidden risk. Even if the main system ships on time, delayed consumables or replacement modules can affect commissioning, warranty performance, and long-term operating reliability.
Regional Market Signals Buyers Should Watch
Regional sourcing conditions are becoming more uneven. Buyers who rely on environmental equipment news for emission control should track not just pricing trends, but also policy shifts, manufacturing utilization, and export conditions by region.
In North America, demand is supported by industrial upgrades, energy transition investments, and stricter site-level compliance expectations. This keeps pressure on engineering capacity and premium system lead times.
Europe remains shaped by energy costs, carbon policy, and industrial modernization. Some suppliers are strong in technology and quality, but buyers may face cost premiums and stricter documentation requirements.
China continues to play a major role in components, fabrication, and complete systems. However, buyers must evaluate quality consistency, certification alignment, export timing, and geopolitical trade exposure before depending heavily on one source.
India and Southeast Asia are becoming more relevant for fabrication and selected equipment categories. Their value proposition is improving, but supplier qualification and project management discipline still require close review.
For multinational buyers, dual-region sourcing is becoming more attractive. It may not always reduce unit price, but it can improve resilience when regulatory changes, customs delays, or local capacity constraints emerge suddenly.
How Regulations Are Changing Procurement Priorities
The strongest demand driver in this market remains regulation. Buyers are not purchasing emission control systems only for efficiency gains. In many cases, procurement decisions are tied directly to permits, audits, expansion approvals, or enforcement deadlines.
That means sourcing risk is also compliance risk. If a late shipment delays installation, the result may be more than a project overrun. It can affect production readiness, plant utilization, or even legal exposure.
In 2026, procurement teams should expect tighter scrutiny around emissions monitoring, energy performance, documentation traceability, and actual field performance versus design assumptions.
This is especially relevant where local authorities are moving beyond simple equipment presence and evaluating measurable outcomes. Buyers should verify whether suppliers can support commissioning data, reporting interfaces, and after-sales compliance support.
Policy interpretation also matters in export projects. A system designed for one jurisdiction may require modifications for another market’s standards, electrical requirements, or emissions thresholds. Those changes can add cost and delay if identified too late.
What Buyers Should Ask Suppliers Before Committing
Procurement teams can reduce uncertainty by asking more precise questions earlier. General quotations are no longer enough when lead time exposure and compliance obligations are both high.
First, ask suppliers to separate total lead time into engineering, material preparation, fabrication, testing, shipment, and commissioning-support phases. This helps identify where schedule risk is concentrated.
Second, confirm which components are made in-house and which rely on external vendors. A supplier with stable fabrication capacity may still be vulnerable if critical controls or imported parts are not secured.
Third, request visibility on reserved capacity. If a quote assumes production slots that are not yet locked, the promised delivery date may be more conditional than it appears.
Fourth, review substitution policies. In a tight market, some vendors may propose equivalent components later in the process. Buyers should define approval requirements for any changes affecting compliance, maintenance, or system integration.
Fifth, evaluate post-installation support. A competitively priced system can become expensive if startup assistance, spare parts, troubleshooting, or emissions tuning are slow or unavailable.
Cost Trends: Why the Cheapest Option May Carry the Highest Risk
Price pressure remains real, especially for buyers managing multiple sites or operating under strict capital controls. But in emission control procurement, the lowest quoted price often hides the highest delivery or operating risk.
Some suppliers offer attractive pricing by excluding commissioning scope, limiting guarantees, delaying component sourcing until after order confirmation, or using less proven sub-suppliers. These choices may not be obvious in headline comparisons.
Procurement should compare offers using total project cost, not only equipment price. Include freight assumptions, installation impacts, energy use, consumables, maintenance intervals, spare parts availability, and downtime exposure.
It is also worth modeling the financial effect of a late delivery. In regulated industries, one delayed system can affect startup schedules, customer commitments, or environmental compliance costs that far exceed the initial purchase savings.
When reading environmental equipment news for emission control, buyers should treat falling commodity prices as only one input. They do not automatically translate into lower delivered cost for engineered environmental systems.
Practical Sourcing Strategies for 2026
The most effective procurement response is not panic buying. It is structured planning. Teams that map technical risk and supplier capacity early are more likely to secure both realistic pricing and reliable schedules.
Start by classifying purchases into three groups: standard consumables, configurable packaged equipment, and custom engineered systems. Each group needs a different sourcing timeline and contract approach.
For custom systems, engage the market earlier than usual. Pre-qualification, technical clarification, and documentation alignment should begin before final budget release where possible.
For critical projects, consider framework agreements or phased purchase orders that secure key components before the full build schedule is finalized. This can reduce exposure to sudden lead time extensions.
Maintain an approved backup supplier list for major categories, but do not assume backup means ready. Alternative vendors should be technically reviewed in advance, not only when the primary source fails.
Procurement should also collaborate more closely with engineering, EHS, operations, and maintenance teams. Many avoidable delays come from late internal decisions rather than external market shortages alone.
What This Means for Buyers in the Months Ahead
For procurement teams, the 2026 market is not defined by one universal shortage. It is defined by uneven risk. Some categories will be manageable, while others will still require early action and careful supplier vetting.
The buyers who perform best will be those who move beyond broad headlines and focus on component-level exposure, compliance requirements, and supplier execution quality. That is where the real decision advantage now sits.
Environmental equipment news for emission control is most useful when translated into purchasing actions: earlier forecasting, smarter supplier questions, stronger contract controls, and a clearer understanding of where delays are most likely.
In short, the market does not call for alarm, but it does demand discipline. 2026 sourcing success will depend less on chasing the lowest quote and more on securing dependable delivery, verified performance, and compliance-ready support.
For buyers planning budgets and projects now, the priority is clear: identify critical categories early, qualify suppliers rigorously, and build flexibility into schedules before supply risk becomes a project problem.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.