Bauxite exports are slowing in some routes but not for one reason

Bauxite exports are slowing on several routes, but the slowdown is not the result of one dominant cause. For buyers, operators, and decision-makers, the key takeaway is this: the market is being reshaped by a combination of shipping bottlenecks, country-level policy changes, refining demand shifts, price relationships across bulk commodities, and broader industrial sentiment. That means procurement risk cannot be judged by export tonnage alone. Companies following mining market updates, refining industry news, construction equipment market trends, and industrial automation news need to watch the full chain—from mine origin and port logistics to alumina capacity and freight availability—before making sourcing or inventory decisions.
Why are bauxite exports slowing on some routes if supply has not collapsed?
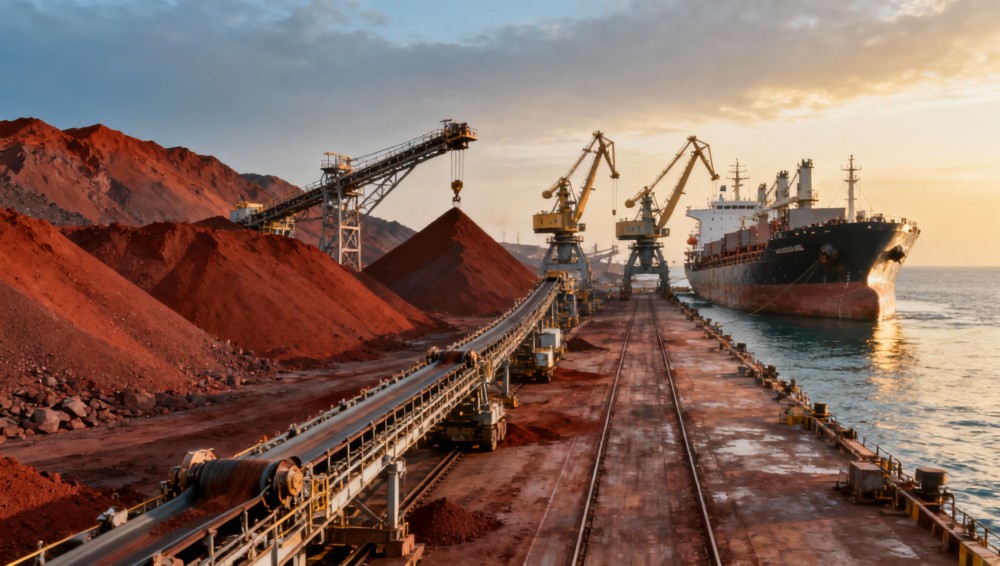
The core search intent behind this topic is not simply to know whether exports are down. Readers want to understand why specific bauxite routes are slowing, whether the trend is temporary or structural, and what it means for pricing, refining operations, and procurement planning.
In practice, the slowdown is route-specific because the bauxite trade depends on a chain of linked variables:
- Port and shipping constraints can reduce cargo flow even when mine output remains stable.
- Regional policy adjustments may affect licensing, export approvals, environmental controls, or local processing requirements.
- Refining capacity changes alter where demand is strongest and which origins remain competitive.
- Freight economics can make some routes less attractive even if ore prices themselves are workable.
- Iron ore and other bulk commodity sentiment influences vessel availability, trader behavior, and market confidence across the dry bulk sector.
So when one route slows, it does not automatically mean the whole bauxite market is weakening. In many cases, flows are being redirected, delayed, repriced, or temporarily constrained by logistics and policy friction rather than by a simple drop in end-use demand.
What are buyers and market researchers most concerned about right now?
For the target audience in this sector, the main concern is not abstract market theory. It is operational impact.
Information researchers want clarity on whether the slowdown signals a broader mining market trend or a narrow disruption tied to certain exporters, ports, or shipping lanes.
Operators and users care about continuity: Will refineries receive feedstock on time? Will quality consistency change if supply shifts to alternative origins? Will inland logistics and stockyard planning need adjustment?
Procurement teams focus on landed cost, freight exposure, supplier reliability, and near-term contract risk. A route slowdown matters only when it changes cost, lead time, or bargaining power.
Business decision-makers are looking for a strategic read: Is this a short-term freight issue, an early warning of tighter supply, or a sign that the bauxite-alumina value chain is entering a more regionalized phase?
The most useful analysis therefore goes beyond export volume headlines and answers four practical questions:
- Which routes are slowing, and which routes are still moving normally?
- Are the causes cyclical, seasonal, regulatory, or structural?
- How does this affect alumina refining costs and downstream industrial supply chains?
- What actions should buyers and planners take now?
Which factors are actually driving the change in bauxite trade flows?
The current picture is best understood as a layered market adjustment rather than a single disruption.
1. Shipping and port-side friction
Bulk mineral exports are highly sensitive to loading efficiency, berth congestion, weather interruptions, draft restrictions, and vessel scheduling. Even a modest slowdown at origin ports can ripple through the trade because bauxite is often moved in large-volume, tightly scheduled cargoes. If vessel turnaround times lengthen, effective export capacity falls even when production is available.
2. Policy and regulatory shifts in exporting regions
In some producing countries, governments are putting greater emphasis on resource control, domestic value addition, environmental compliance, or more selective export oversight. These changes may not stop exports altogether, but they can slow approvals, change shipment timing, or alter the economics of serving particular overseas refiners.
3. Refining capacity and demand rebalancing
Bauxite exports ultimately depend on alumina refining demand. When refining margins weaken in one region or new capacity rises in another, trade routes adjust. Some importers may reduce spot purchases, prefer different ore grades, or shift to suppliers with better freight positions. This is why export slowdowns on one route may coincide with steadier shipments elsewhere.
4. Mineral price trends and substitution logic
When commodity prices move, trade behavior changes. Not just because ore prices rise or fall, but because producers, traders, and end users reassess margins across the chain. In a tighter margin environment, higher freight or handling costs can quickly make a route less attractive. In stronger pricing conditions, the same route may remain viable despite inefficiencies.
5. Iron ore market sentiment and dry bulk spillover
This is an underappreciated issue. Bauxite does not trade in isolation. Iron ore market sentiment influences the broader dry bulk market, including freight rates, vessel deployment, and trader expectations. If iron ore volumes or sentiment shift sharply, the secondary effects can reshape shipping economics for bauxite exporters and importers.
What does this mean for refining, machinery, and industrial supply chains?
For readers in manufacturing, processing machinery, industrial equipment, and electrical equipment sectors, the importance of bauxite exports goes beyond mining headlines. Bauxite feeds alumina, alumina feeds aluminum, and aluminum remains a critical material across machinery, transport equipment, electrical systems, components, and plant infrastructure.
If route-specific bauxite slowdowns continue, the main supply chain implications are likely to include:
- More volatile raw material planning for alumina and aluminum-linked buyers.
- Wider landed-cost differences by destination, especially where freight is a large share of delivered cost.
- Greater emphasis on supplier diversification rather than dependence on one origin or one corridor.
- Potential shifts in refining utilization if feedstock timing becomes less predictable.
- Longer decision cycles for procurement and investment as companies wait for better visibility on policy and logistics conditions.
This matters for construction equipment market participants as well. Machinery production depends on stable metal inputs, and even when bauxite is not a direct procurement item, upstream disruption can feed into aluminum pricing, component lead times, and supplier negotiations.
For companies tracking industrial automation news, the broader lesson is that supply chain visibility tools are becoming more valuable. When disruptions are caused by multiple moderate factors instead of one major event, businesses need better data integration across shipping, commodity pricing, port movement, and supplier performance.
How should procurement teams and decision-makers respond?
The best response is not panic buying or broad assumptions about “tight supply.” It is disciplined monitoring and route-level risk management.
For procurement teams:
- Review exposure by export origin, not just by supplier name.
- Track freight and port conditions alongside ore pricing.
- Separate short-term shipping disruption from long-term regulatory risk.
- Assess whether alternative origins match required ore quality and refining performance.
- Use scenario-based sourcing plans for normal flow, delayed shipment, and route reallocation cases.
For plant operators and supply planners:
- Monitor inventory coverage against realistic delivery variability, not average historical transit times.
- Coordinate more closely with logistics teams on vessel timing and discharge planning.
- Watch for changes in ore blend quality if procurement shifts origins.
For executives and commercial leaders:
- Focus on whether route slowdowns are changing competitive positioning in your region.
- Evaluate whether long-term contracts still reflect current logistics and policy realities.
- Invest in supply chain intelligence where commodity, policy, and freight signals can be viewed together.
The companies most likely to perform well in this environment are those that treat bauxite export trends as a multi-variable risk signal, not as a one-number market indicator.
Is this a temporary disruption or a more durable market shift?
At this stage, the most balanced judgment is that the slowdown on some bauxite export routes reflects a mixed market condition. Some pressures are temporary, such as shipping delays, weather impacts, and short-term freight dislocation. Others may prove more durable, especially where policy direction favors domestic processing, tighter resource oversight, or structural changes in refining geography.
That is why a simple bullish or bearish conclusion is not especially useful. The better conclusion is this: bauxite trade is becoming more sensitive to route economics, policy timing, and downstream processing dynamics. As a result, market participants should expect more uneven performance between corridors rather than a uniform global trend.
For search users asking why bauxite exports are slowing, the answer is clear: they are slowing in some routes because several pressures are converging at once—shipping, regulation, refining demand, price relationships, and bulk market sentiment. But because these drivers vary by region, origin, and destination, the slowdown should be read as a trade pattern adjustment rather than a single-cause market breakdown.
In summary, bauxite exports are not weakening for one reason, and they are not weakening everywhere in the same way. For researchers, operators, buyers, and business leaders, the real value lies in understanding which routes are affected, why those routes are changing, and how that impacts refining costs, procurement choices, and industrial supply chains. The right approach now is careful route-level analysis, stronger supply chain visibility, and more flexible sourcing decisions rather than headline-driven assumptions.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.