Machine Tools Market Analysis: Demand Drivers, Capacity Shifts, and Investment Risks
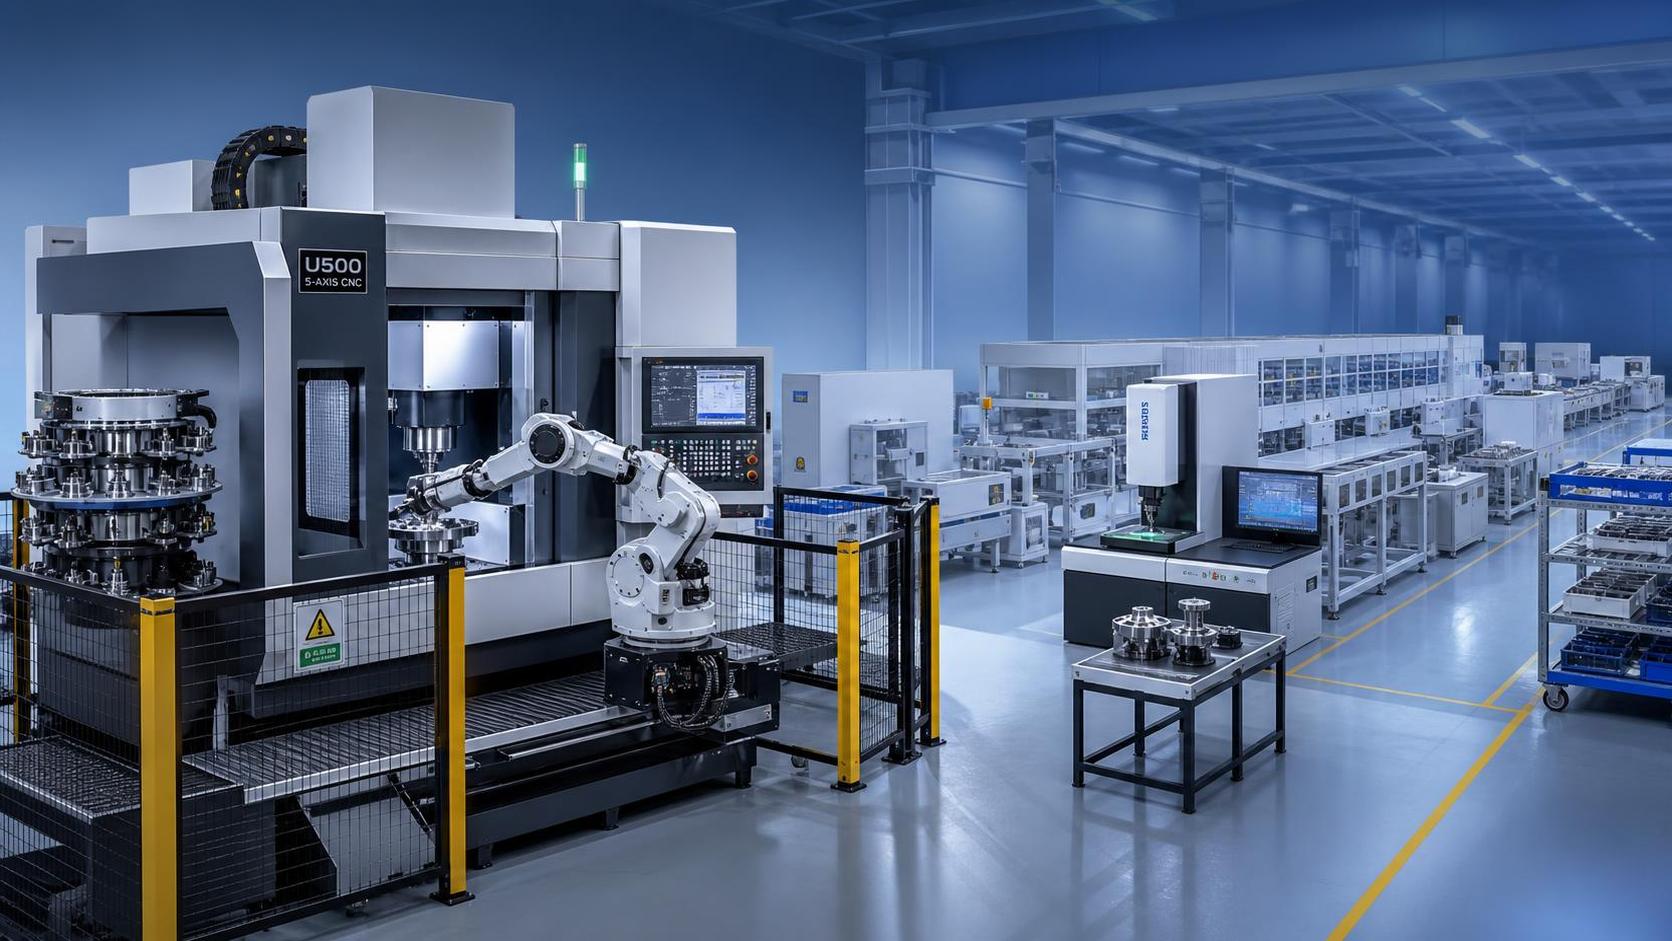
Machine tools sit at the intersection of industrial confidence and industrial capability. When manufacturers expect sustained orders, they invest in new machining centers, turning systems, grinding equipment, controls, tooling, and automation. When demand becomes uncertain, machine tool spending is often delayed before other operating costs are cut. That makes machine tools market analysis useful not only for equipment suppliers, but also for manufacturers, procurement leaders, investors, distributors, and companies planning regional production capacity.
The current market is being shaped by several forces that do not always move in the same direction. Demand for higher precision, shorter lead times, automated production, and localized supply chains continues to support investment. At the same time, weak end-market visibility, high financing costs in some regions, skilled-labor constraints, and uneven industrial output can cause buyers to defer major capital expenditure. The result is not a simple expansion or contraction cycle. It is a more selective market in which the application, customer segment, country of operation, and technology level matter more than headline demand alone.
Machine tool demand is becoming more selective
A broad reading of factory investment can be misleading. Demand for machine tools is increasingly concentrated in applications where productivity, accuracy, traceability, or supply security have a direct commercial value. Aerospace components, medical devices, energy equipment, semiconductor-related infrastructure, precision automotive parts, defense production, and advanced general engineering may continue to require investment even when lower-value production remains cautious.
For decision-makers, this distinction matters. A rise in industrial machinery orders does not automatically mean that every category of machine tool will benefit equally. A standard three-axis machining center serving price-sensitive subcontractors faces a different market than a multi-axis system integrated with automated loading, in-process measurement, and digital production monitoring. Both are “machine tools,” but their demand drivers, buyer profiles, margins, and exposure to cyclical pressure are different.
In many markets, buyers are moving from equipment replacement toward capability investment. They are asking whether a new machine can reduce labor dependence, consolidate multiple operations, improve first-pass yield, support a new material, or qualify the plant for higher-value work. This changes the sales conversation. Technical specifications remain important, but the business case increasingly depends on total throughput, uptime, programming efficiency, service response, and integration with existing processes.
A useful question for buyers is not simply whether machine tool demand is rising. It is whether their target customers are investing to add volume, replace aging capacity, improve quality, move production closer to end users, or meet a new compliance requirement. Each motive produces different buying behavior and different risk.
Automation is supporting investment, but not every automation project pays back
Labor availability remains one of the strongest structural drivers of machine tool modernization. In established manufacturing economies, experienced operators, programmers, maintenance technicians, and toolmakers are difficult to replace. In developing production hubs, labor may still be cost-competitive, but turnover, training demands, and higher quality expectations are pushing factories toward more repeatable processes.
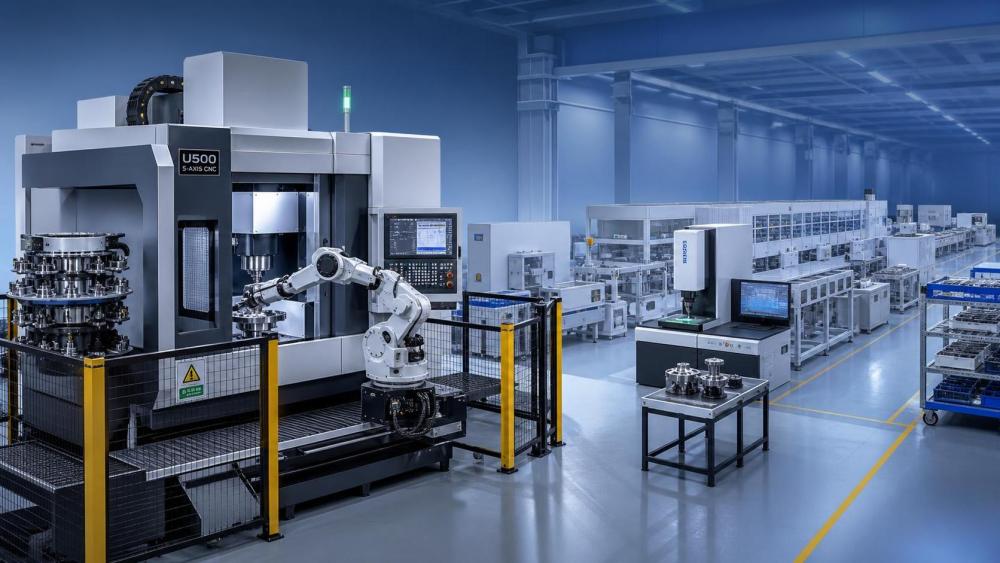
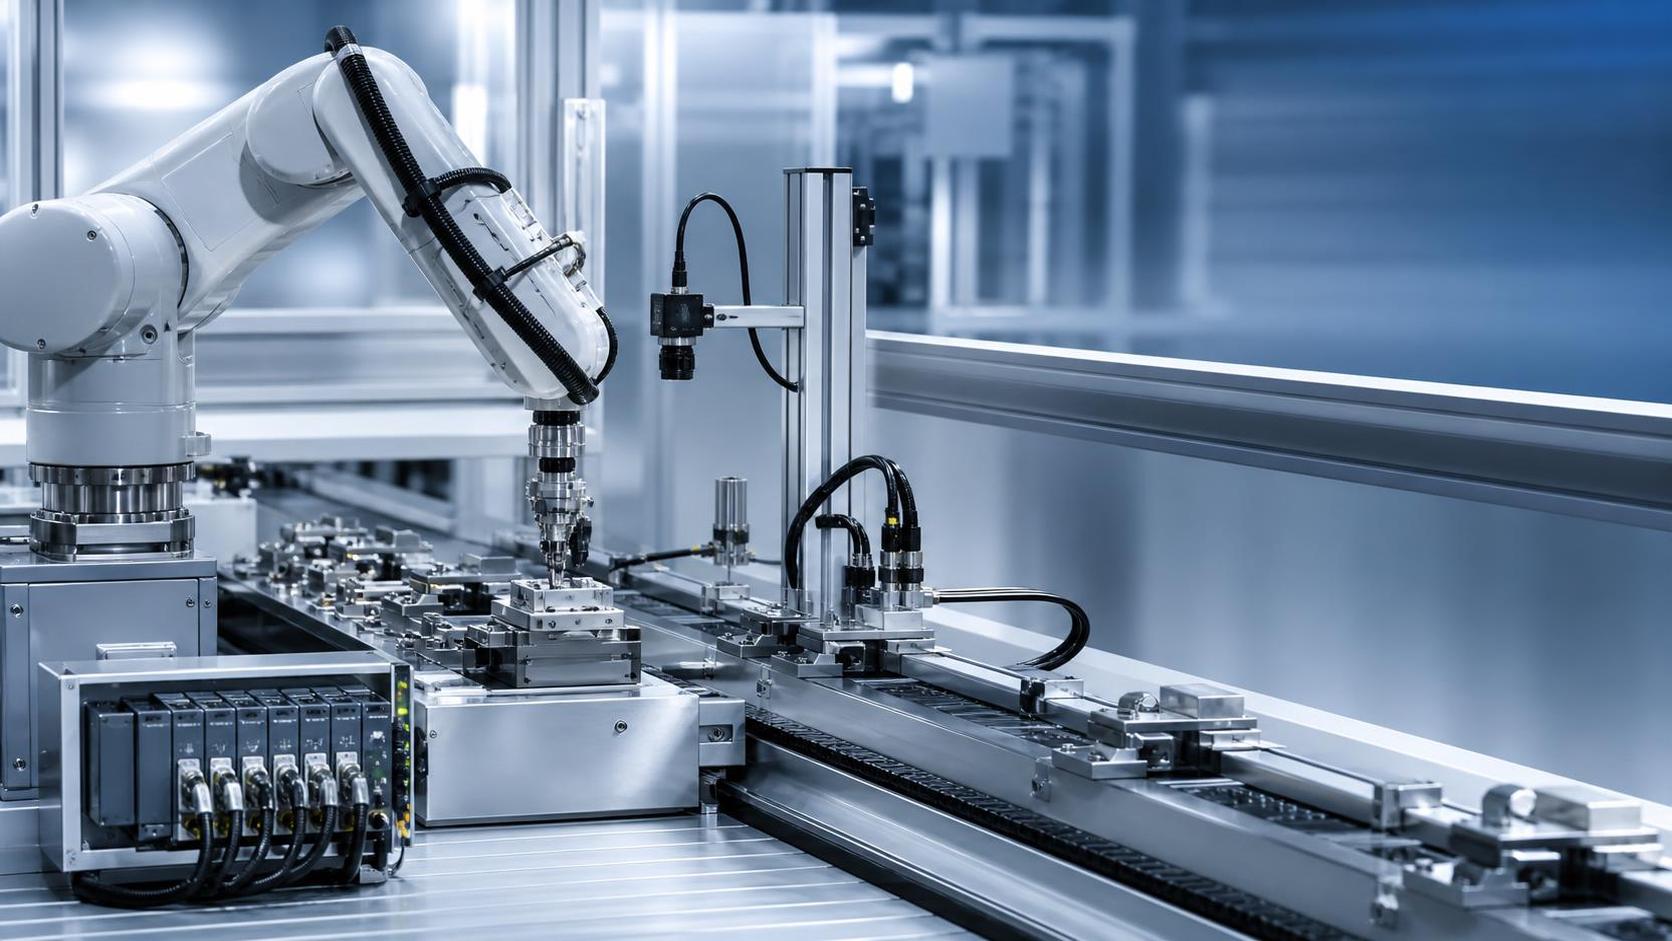
That environment supports demand for pallet systems, bar feeders, robotic tending, automatic tool management, workpiece measurement, remote diagnostics, and manufacturing execution software. However, automation should not be treated as a universal answer. A factory with highly variable batch sizes, frequent engineering changes, unstable incoming material quality, or poorly standardized fixturing may not achieve the expected return from unattended machining.
Many automation investments fail to meet their original business case because the machine is evaluated in isolation. The bottleneck may actually sit in programming, part inspection, tooling preparation, material staging, changeovers, or downstream finishing. A robot can improve spindle utilization, but it cannot solve a process that lacks stable cycle times or reliable workholding.
Before committing to an automated machine tool cell, companies should test several operational assumptions:
- Can the planned part family use common fixtures, tools, and handling methods?
- Is annual volume sufficient to justify engineering, integration, and maintenance costs?
- Can the production team support offline programming and process optimization?
- Are raw materials, cutting tools, and inspection capacity available without creating new bottlenecks?
- Does the supplier provide local commissioning, application support, spare parts, and control-system expertise?
The strongest projects are usually those that begin with a specific constraint: recurring operator shortages on a stable part family, an inability to meet delivery targets, excessive setup time, or a quality problem that requires tighter process control. Projects built only around a general ambition to “automate” deserve closer scrutiny.
Capacity is shifting, but localization does not mean full self-sufficiency
Regionalization is another major theme in the machine tools market. Manufacturers in North America, Europe, India, Southeast Asia, Mexico, and parts of the Middle East are pursuing new or expanded capacity in response to supply-chain disruptions, trade friction, customer localization requirements, and industrial policy. This has increased interest in local production ecosystems, including machining, casting, tooling, controls, electrical components, and aftermarket service.
Yet the idea that production can quickly become fully local is often overstated. Machine tools rely on complex supply chains. High-precision components, linear guides, ball screws, spindles, CNC controls, servo systems, encoders, bearings, castings, and specialty tooling may originate from different countries. A plant can assemble machines locally while remaining exposed to imported components, software licenses, or specialist service expertise.
For equipment buyers, the key issue is not the nationality of the final machine assembly alone. It is the resilience of the support chain. Procurement teams should ask where critical parts are made, how long replacement components take to arrive, whether alternative sources exist, and whether local technicians can resolve control, spindle, geometry, and application issues. A low purchase price can become expensive when a critical machine remains idle for weeks awaiting a component or a qualified service engineer.
Capacity shifts also create a competitive challenge for established suppliers. New regional manufacturing investment can expand the addressable market, but it can also encourage domestic machine builders, lower-cost entrants, and system integrators to compete for customers who previously relied on imported equipment. The competitive advantage of global brands is therefore moving beyond machine performance toward application engineering, installed-base support, financing, training, software integration, and credibility in regulated sectors.
End-market exposure matters more than broad manufacturing sentiment
Machine tools are a capital-goods market, but they are ultimately driven by downstream production programs. Automotive remains important because of its scale, though its investment pattern is changing. Electrification can reduce machining demand for certain internal-combustion-engine components while increasing demand for battery manufacturing equipment, thermal management components, e-axle housings, power electronics, lightweight structures, and specialized tooling. The transition is uneven, and suppliers exposed to legacy powertrain machining should avoid assuming that all automotive investment will compensate for lost component volumes.
Aerospace and defense can offer longer program cycles and high-value machining requirements, but qualification barriers are substantial. Suppliers need to demonstrate process control, material capability, documentation, and delivery consistency. Energy-sector demand can be attractive for large components, valves, turbines, pumps, transmission equipment, and infrastructure, but it may be exposed to project timing, commodity cycles, and public investment decisions.
General engineering often provides the widest customer base and the greatest volatility. Small and medium-sized job shops may respond quickly to local orders but can also defer purchases when financing becomes expensive or order books weaken. In this segment, the availability of used machines, leasing, refurbished equipment, and trade-in programs can materially affect new-machine demand.
The implication is straightforward: suppliers and investors should build market views from end-use applications upward, rather than relying only on national manufacturing indicators. A region can show stable industrial output while a specific machine category weakens because its main customer base is overcapacity, shifting technology, or cutting inventories.
Technology differentiation is widening the gap between suppliers
Machine tool competition is no longer defined only by spindle speed, axis count, or nominal cutting capacity. Buyers increasingly compare equipment based on reliability over long production runs, ease of programming, energy efficiency, digital connectivity, measurement integration, automation readiness, and the supplier’s ability to support difficult applications.
This favors companies that can combine mechanical engineering with controls, software, tooling knowledge, and local service. It also creates room for specialized suppliers focused on a narrow but defensible application: complex five-axis machining, gear production, precision grinding, large-part machining, composite processing, or high-volume automated turning.
However, technology claims need to be tested against the operating environment. A highly capable machine may be unnecessary for a shop producing simple, low-margin parts. Conversely, a lower-cost machine may create hidden costs if it struggles with repeatability, tool life, thermal stability, documentation, or integration. The relevant comparison is not feature count. It is cost per acceptable part over the machine’s practical working life.
Procurement teams should require evidence from comparable applications where possible. Demonstration parts, cycle-time studies, sample material tests, machine availability records, and service references are more useful than generic brochures. For complex installations, acceptance criteria should cover not just machining accuracy but also setup time, automation recovery, measurement results, data connectivity, operator training, and spare-parts commitments.
Investment risk is rising where expansion assumptions are weak
Capital investment in machine tools carries several layers of risk. The most visible is demand risk: a manufacturer buys capacity based on expected orders that do not materialize. But technical and operational risks can be just as damaging. A machine may arrive late, require longer-than-planned commissioning, fail to achieve the expected cycle time, or remain underutilized because the factory cannot recruit or train the necessary personnel.
Financial conditions also matter. Higher interest rates, tighter working capital, and slower customer payments can change the economics of an otherwise sound equipment project. Companies should model realistic ramp-up periods rather than assuming immediate full utilization. They should also account for tooling, fixtures, metrology, facility upgrades, electrical work, compressed air, coolant management, software, operator training, and maintenance. These costs are frequently underestimated when investment decisions focus too narrowly on the machine purchase price.
For investors, a key warning sign is capacity expansion without a credible application advantage. Adding standard equipment into an already competitive market may increase revenue temporarily but weaken pricing and returns over time. More defensible investment tends to be linked to customer qualification, specialized process knowledge, regional service coverage, or a production bottleneck that competitors cannot easily replicate.
There is also a risk in treating reshoring announcements as confirmed machine demand. Public commitments, industrial incentives, and site announcements can take years to translate into operating factories. Some projects are resized, delayed, or redirected as market conditions change. Equipment suppliers should distinguish between announced investment, funded construction, installed production lines, and recurring consumables or service demand.
What decision-makers should watch next
The next phase of the market will likely be defined less by a single global growth rate than by the quality of industrial investment. Companies should monitor whether production programs are moving from announcement to equipment ordering, whether machine utilization is improving at key customers, and whether automation projects are being expanded after initial deployment. These are stronger indicators of durable demand than broad promotional claims around smart manufacturing or reshoring.
Attention should also remain on control-system availability, export restrictions, energy costs, financing conditions, and the ability of local service networks to support a growing installed base. These factors can influence purchase decisions as much as the machine itself.
For manufacturers, the practical priority is to match equipment investment to a defined production problem and a realistic demand horizon. For suppliers, the opportunity lies in proving operational value beyond the sale. For investors, the most attractive positions may be found where capacity, application knowledge, and service capability reinforce one another. In a more fragmented industrial landscape, the machine tool market rewards disciplined execution more reliably than broad optimism.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.
- industrial equipment
- industrial machinery
- procurement
- manufacturing
- equipment suppliers
- machine tools
- smart manufacturing
- pumps
- valves
- bearings
- production capacity
- manufacturing equipment
- power electronics
- energy efficiency
- energy equipment
- mechanical engineering
- machine tools market
- machine tools market analysis