Industrial Components Market Trends: What Buyers Should Watch in Supply, Pricing, and Demand
Industrial components market trends are moving in a way that feels familiar and different at the same time. Buyers are still dealing with old problems—lead times, price changes, supplier reliability—but the signals behind those problems have become harder to read. A shortage in one category may sit next to oversupply in another. A quoted price may reflect raw material movement, freight uncertainty, exchange-rate pressure, or simply a supplier trying to protect allocation.
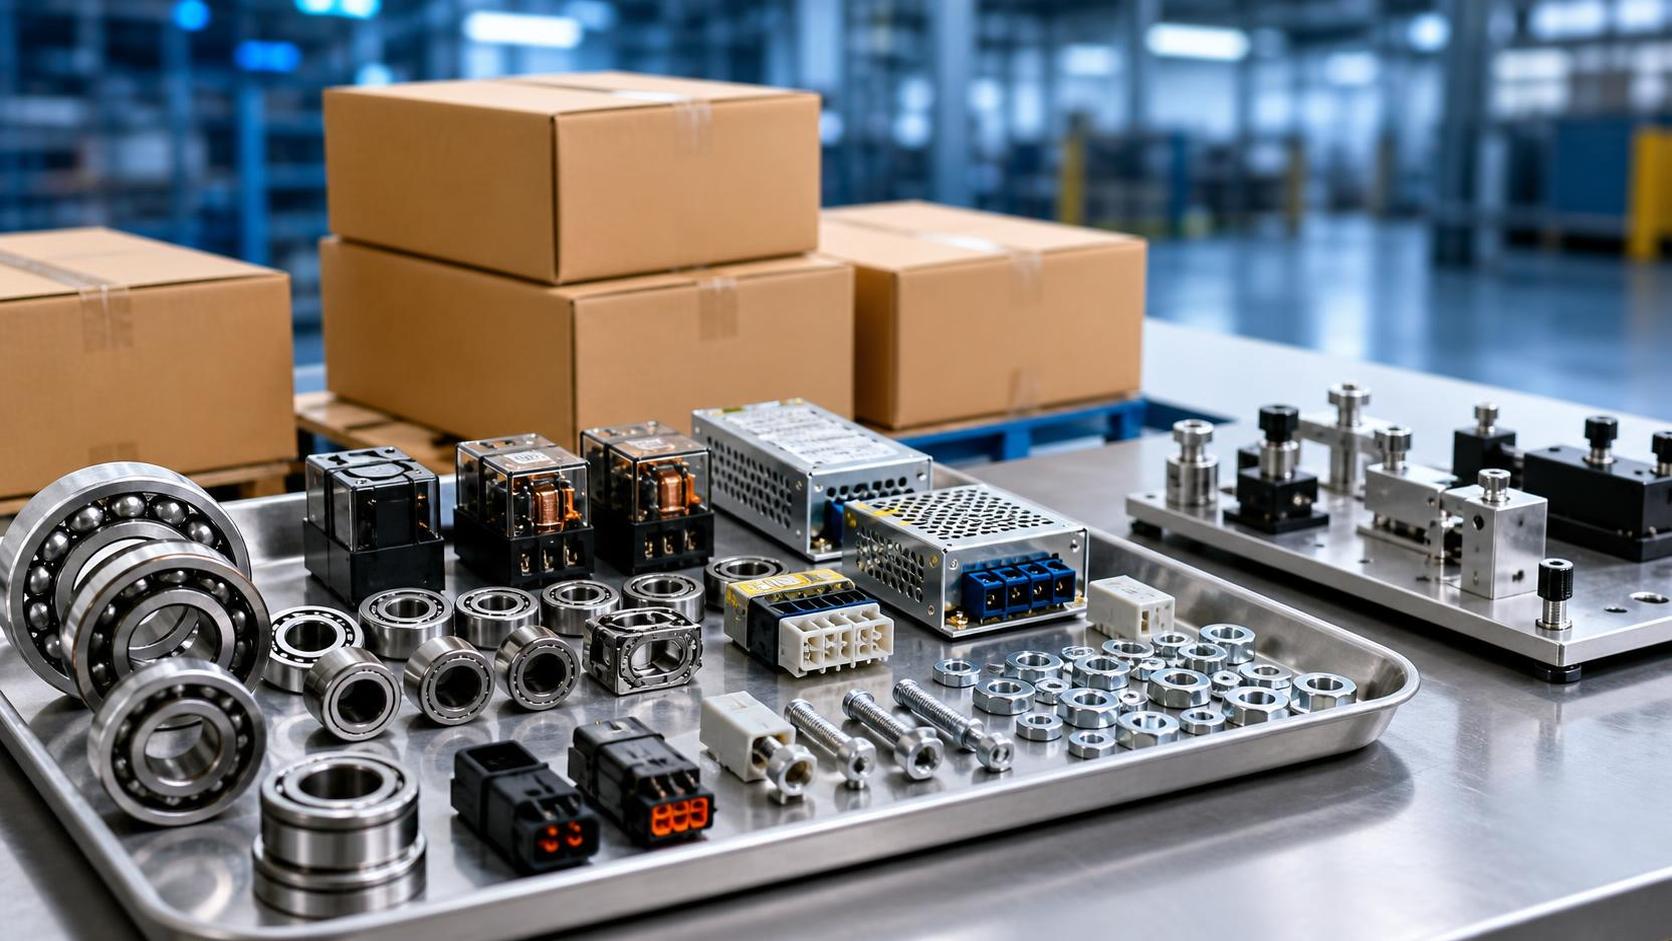
For procurement teams, that means market awareness is no longer just a background task. It directly affects sourcing strategy, inventory decisions, and even whether a project schedule can hold. In industrial supply chains, components that look interchangeable on paper often are not. A bearing, contactor, connector, drive module, fastener, seal, relay, or power supply can become a bottleneck if the approved source list is too narrow or if technical substitution is more complicated than expected.
What matters now is not only knowing that the market is volatile, but understanding where volatility is coming from and which indicators deserve attention before issuing POs or committing to long-term supply agreements.
Supply is no longer a single issue
Many buyers still talk about “supply tightness” as if it applies evenly across industrial components. It rarely does. In practice, availability now varies by product family, origin, specification complexity, and approval requirements. Standard mechanical parts may normalize faster than custom machined items. Some electrical components remain sensitive because they depend on a narrower semiconductor or specialty material base. Even when factories have capacity, bottlenecks can shift to sub-tier parts, testing slots, export documentation, or transport lanes.
This is why lead time alone can be a misleading metric. A supplier quoting a shorter delivery window is not automatically the safer option if that promise depends on unconfirmed incoming materials or on production slots that are not yet secured. Buyers need to ask a more useful question: where exactly is the constraint? Is it casting, winding, PCB assembly, plating, heat treatment, packaging, outbound shipping, or customs clearance? The answer changes the risk profile.
In categories tied to maintenance demand, supply can also tighten unexpectedly because aftermarket consumption is less visible than project demand. Plants often delay replacement purchases until failure risk becomes unacceptable, then many orders hit the market at the same time. That pattern can distort the apparent balance between supply and demand.
A useful habit is to separate components into three groups: easy-to-switch items, technically sensitive items, and approval-locked items. The last group deserves the closest monitoring because an alternative source may require engineering review, customer approval, testing, or compliance checks that take far longer than the component lead time itself.
Pricing is being shaped by more than raw materials
Buyers often expect component prices to track steel, copper, aluminum, or energy costs in a straightforward way. Sometimes they do. Often they do not. In the current market, pricing behavior is affected by a wider mix of variables: production planning confidence, order backlog quality, labor cost, localization strategy, container availability, currency shifts, and how aggressively suppliers are trying to rebuild margins after previous disruptions.
That creates a common problem in sourcing reviews. Two suppliers may quote similar products at noticeably different levels, and the gap cannot be explained by material cost alone. One may be carrying higher safety stock. Another may have better upstream contracts. A third may be pricing in risk because the specification is likely to change or because annual volume is too uncertain to reserve capacity efficiently.
This is where procurement needs to move beyond unit price comparison. Total acquisition cost matters more when markets are unstable. A lower nominal price can be offset by packaging changes, partial shipments, inspection burden, higher defect exposure, or a need to hold more inventory. For imported parts, payment terms and exchange-rate timing can also alter the real cost enough to affect sourcing decisions.
It is also worth watching how suppliers structure validity periods. Short validity windows usually signal uncertainty, but they can mean different things. In some cases, the supplier is exposed to commodity movement. In others, the supplier is unsure about inbound logistics or factory loading. Procurement teams that understand this distinction are in a stronger position to negotiate smarter mechanisms—such as indexed adjustments, staggered releases, or split-volume awards—instead of arguing only over the first quote.
Demand is uneven, and that matters more than headline market sentiment
The demand side of industrial components is not moving in one direction. Capital equipment orders, maintenance cycles, infrastructure work, export manufacturing, energy projects, and plant automation upgrades do not peak at the same time. Buyers who rely only on broad industrial sentiment can miss what is happening in their specific categories.
For example, a general slowdown in one manufacturing segment does not necessarily reduce pressure on components serving electrification, grid-related work, food processing upgrades, warehouse automation, or critical maintenance. In fact, weak end-market conditions sometimes increase demand for retrofit parts because operators extend the life of existing equipment instead of investing in complete replacement.
This unevenness affects buying behavior in a practical way. If your component portfolio serves both OEM production and MRO demand, the same supplier may prioritize one order stream over another. Buyers should ask whether current backlog is coming from project business, recurring distribution demand, or emergency replacement orders. Those demand patterns influence allocation and service levels.
It also helps to watch exhibitions, company expansion announcements, policy changes related to industrial investment, and regional manufacturing activity—not because any one signal gives a complete answer, but because together they show where capacity competition may build next. This is where an information platform such as NEXUSINSIGHTS can be genuinely useful: not as a sales channel, but as a way to connect scattered developments across machinery, electrical equipment, automation systems, mechanical parts, and global supply chains into something decision-makers can actually use.
What experienced buyers watch before a shortage becomes visible
Good procurement teams rarely wait for a formal shortage notice. They look for smaller signals that usually appear first.
- Repeated quote revisions within a short period
- Suppliers pushing partial deliveries instead of consolidated shipments
- Growing reluctance to commit to blanket order schedules
- Specification clarification requests increasing late in the RFQ stage
- More discussions around alternate brands, materials, or country of origin
- Longer approval cycles for components that used to be routine
None of these signals proves a market shift by itself. Together, they often show that supply confidence is weakening. The point is not to overreact. It is to update sourcing priorities early enough to avoid being forced into high-cost, low-choice purchases later.
Why second-source planning is harder than it sounds
In theory, broadening the supplier base reduces risk. In real industrial procurement, second-source strategy often fails because teams underestimate the friction outside commercial terms. A part may match dimensions and still create problems in tolerance stack-up, material behavior, electrical compatibility, connector pinout, mounting pattern, firmware version, documentation quality, or required test records.
That is especially true for components inside larger assemblies, safety-related systems, export equipment, or projects with strict end-user approval processes. Switching a low-value item can trigger costly revalidation. This is why a good market read has to sit next to technical discipline. Buyers should map which components are commercially interchangeable and which are operationally locked, then invest time accordingly.
A practical approach is to prequalify alternatives before the market becomes stressed. That does not mean duplicating every source. It means identifying where the cost of qualification is justified by the cost of future disruption.
Regional sourcing still matters, but not for the old reasons alone
Regional diversification is no longer just about freight time. Buyers are increasingly balancing origin strategy against policy exposure, customs predictability, after-sales support, documentation standards, and customer expectations around traceability. For some categories, nearshoring improves responsiveness. For others, it only adds cost if the regional supplier still depends on imported subcomponents with the same underlying risk.
This is where many sourcing discussions become too simplistic. “Local” supply can still be globally exposed, while “overseas” supply can be stable if the supplier has strong process control, better inventory discipline, and clearer export execution. Buyers need to assess the actual chain, not just the final shipping point.
For cross-border purchasing, details that once felt secondary—HS classification accuracy, origin declarations, packing method, replacement-part labeling, and documentation consistency—can affect landed reliability as much as production lead time. Those items deserve attention early, especially when industrial components are moving into regulated sectors or project-based deliveries.
How to make market information useful in day-to-day procurement
Market intelligence only helps if it changes action. Procurement teams do not need more noise; they need a workable filter. In most industrial organizations, that means linking external market signals to an internal component matrix: criticality, annual spend, lead-time exposure, substitute difficulty, certification sensitivity, and supplier concentration.
Once that matrix exists, updates become easier to prioritize. A policy change affecting electrical equipment imports may matter immediately for one business unit and barely at all for another. A company expansion in a heavy manufacturing cluster may signal future competition for castings, motors, controls, or mechanical transmission parts. Trade shows and supplier announcements can also hint at where production is being added, where technology is shifting, and which categories may see more stable availability over time.
This is one reason specialized platforms remain relevant in B2B industry research. NEXUSINSIGHTS sits in a space where machinery, industrial equipment, automation, power supplies, mechanical components, and global trade activity intersect. For buyers, the value is not in consuming more headlines. It is in spotting relationships between market movement, supplier behavior, and sourcing opportunity before those factors hit a live project.
Industrial components market trends will continue to shift by category, region, and application. Buyers who treat all components the same will keep running into avoidable surprises. The better approach is more selective: monitor supply constraints at the sub-tier level, read price changes in context, separate real demand pressure from general market mood, and qualify alternatives before they are urgently needed. When the next disruption appears—and it usually does—the teams that already understand their technical dependencies, delivery exposure, and supplier structure will have more room to act.
If there is one practical next step, it is this: review your top-risk component groups now, not after lead times extend. Confirm which items are approval-locked, which quotes are carrying hidden risk, and which suppliers can explain their capacity and sourcing position clearly. In this market, that level of visibility is often the difference between a manageable adjustment and a costly scramble.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.