Industrial Automation Market in Southeast Asia: Key Drivers, Opportunities, and Risks
Industrial Automation Market in Southeast Asia: Key Drivers, Opportunities, and Risks
The industrial automation market in Southeast Asia is moving from selective factory upgrades toward broader production-system redesign. Manufacturers are not investing in automation simply to reduce headcount. They are trying to stabilize output, improve traceability, manage tighter delivery expectations, and make plants less vulnerable to labor shortages, quality variation, and supply-chain disruption.
That shift matters because Southeast Asia is not one uniform manufacturing market. Singapore’s advanced electronics and process industries, Vietnam’s export-oriented production base, Thailand’s automotive and food-processing ecosystems, Indonesia’s large domestic industrial base, and Malaysia’s electrical and semiconductor-linked manufacturing all create different demand patterns. The same robotics cell, PLC architecture, or industrial software package may have a very different business case depending on local labor availability, utility reliability, plant maturity, export requirements, and the strength of nearby engineering support.
For business leaders, the central question is no longer whether automation will expand. It is where investment can deliver measurable operational control without creating difficult integration, maintenance, or cybersecurity burdens. The strongest projects tend to start with a defined bottleneck: unstable cycle times, recurring defects, manual inspection limits, unsafe material handling, energy waste, or inadequate production visibility.
Why Automation Demand Is Building Across the Region
Several forces are converging. Manufacturers serving international customers face closer scrutiny of quality records, component traceability, delivery consistency, and process documentation. Manual production can remain economical in some applications, but it becomes harder to control when product variants increase or when customers require reliable data from each production stage. Sensors, machine vision, manufacturing execution systems, and connected controllers help make production events visible rather than dependent on handwritten records or informal reporting.
Labor economics are another driver, although they should not be oversimplified. Wage pressure matters, but automation decisions are often prompted by difficulty recruiting and retaining skilled operators for repetitive, hazardous, or precision-dependent work. In packaging, welding, electronics assembly, palletizing, and inspection, the issue may be less about replacing people than about redeploying them to tasks that require judgement, process knowledge, and maintenance capability.
The region is also benefiting from continued supply-chain diversification. As manufacturers build or expand production capacity outside a single country, new facilities offer an opportunity to install modern control layers from the start. Greenfield plants can specify network architecture, safety systems, power quality monitoring, and data collection before legacy equipment creates constraints. Existing factories face a different reality: they must integrate new equipment with older machines, mixed protocols, and maintenance teams accustomed to established working methods.
Energy management is becoming a more practical part of the automation conversation. Motors, drives, compressed-air systems, cooling equipment, and process heating can account for meaningful operating costs, yet many plants still lack granular visibility into how energy is consumed by line, shift, or process step. Automation does not automatically reduce energy use, but metering, variable-speed drives, production scheduling, and condition monitoring can give teams the information needed to identify avoidable consumption.
Where Investment Is Concentrating
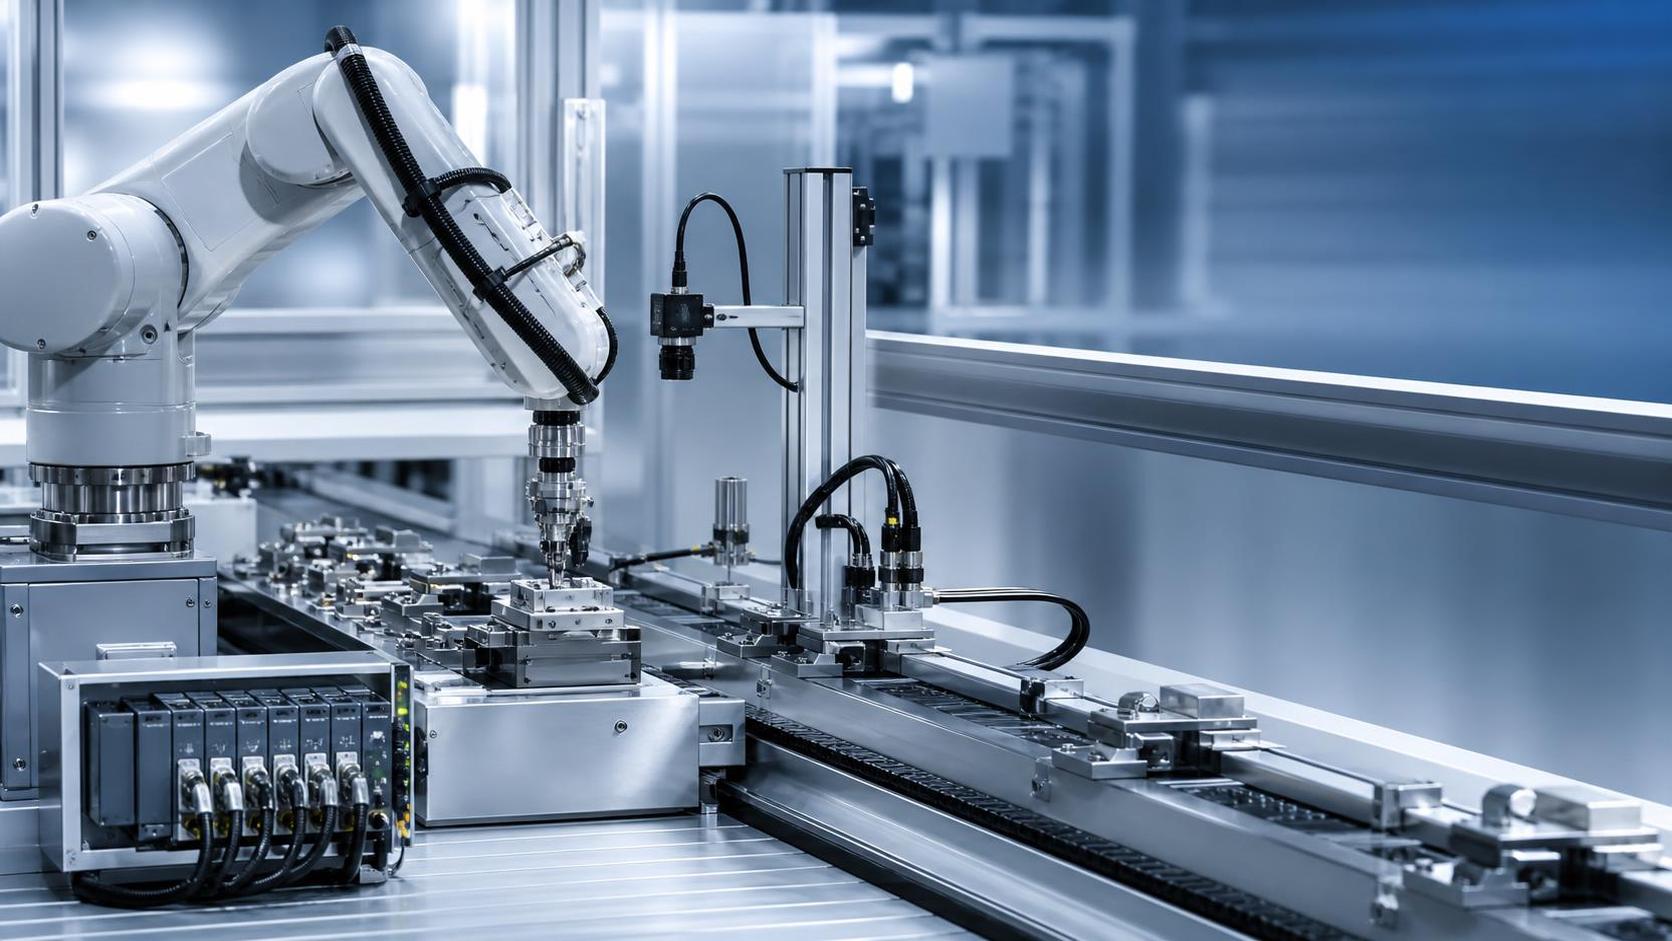
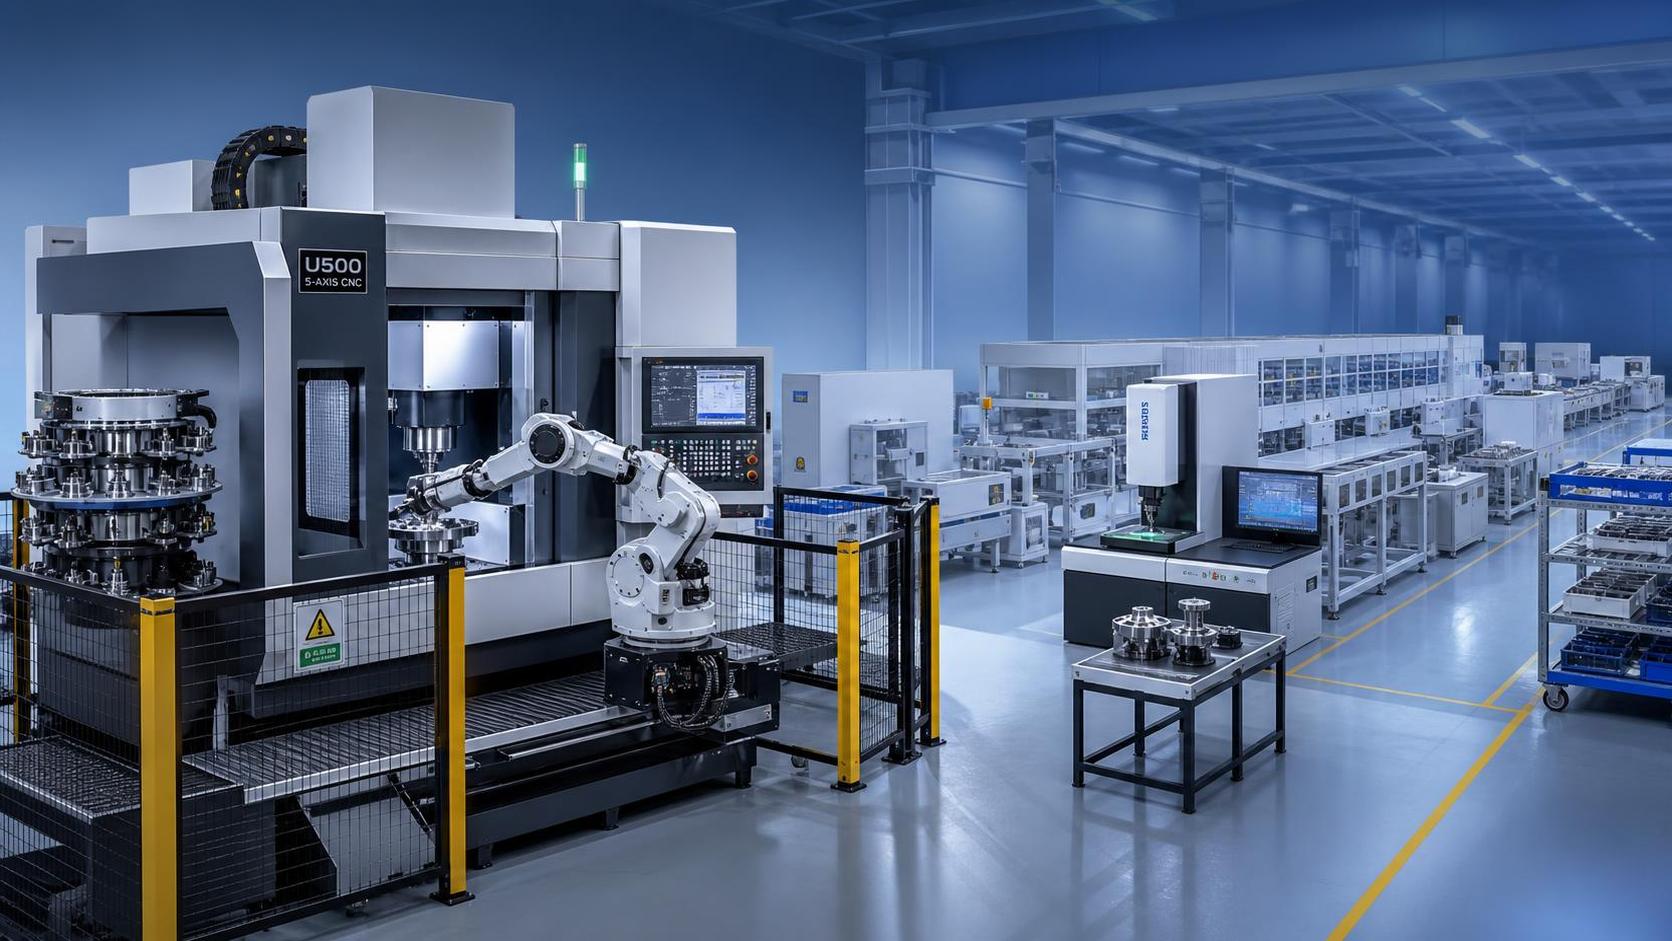
Demand is spread across a wider equipment stack than industrial robots alone. Robotics attracts attention because it is visible on the factory floor, but many Southeast Asian plants are first investing in less dramatic upgrades: PLC replacement, servo systems, safety controls, sensors, industrial networking, SCADA modernization, machine vision, and remote diagnostics. These investments can improve reliability and data quality without requiring a complete production-line rebuild.
Electronics manufacturing remains a major automation field because precision, repeatability, handling sensitivity, and traceability are tightly connected. Automated optical inspection, component handling, test systems, clean-production controls, and digital work instructions are particularly relevant. In automotive and metalworking, demand often centers on welding, assembly verification, in-line inspection, machining-cell loading, and material flow. Food, beverage, and consumer goods producers are more likely to focus on packaging automation, batch control, hygienic design, weighing, labeling, and warehouse movement.
Warehouse automation deserves separate attention. E-commerce growth and more complex distribution networks have increased interest in conveyors, sortation, automated storage, mobile robots, barcode or RFID-based tracking, and warehouse management software. Yet a warehouse project should not begin with a robot selection. Slotting logic, SKU profile, order volatility, carton dimensions, picking methods, and building layout often determine whether automation will be useful or underutilized.
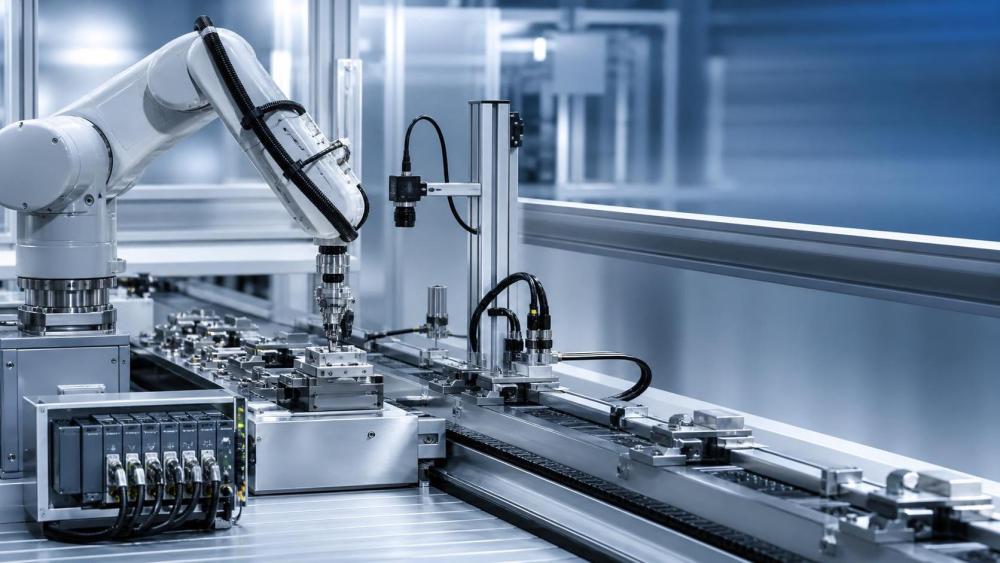
The opportunity differs by automation layer
Country Differences Shape the Real Business Case
Singapore is often associated with high-value manufacturing, advanced process control, and digital industrial systems. Projects there may place a premium on throughput, data integrity, specialized engineering, and integration with regional operations. The economics of highly manual processes can be less attractive where skilled labor is scarce or costly, but the expectations for system reliability and cybersecurity are also higher.
Vietnam continues to draw attention from companies building export manufacturing capacity, particularly in electronics, appliances, machinery-related supply chains, and consumer goods. Automation demand may emerge in stages: a new line begins with basic control and semi-automatic stations, then adds inspection, handling, and digital tracking as volumes and quality requirements rise. The availability of capable local integrators and technicians can be as decisive as the equipment specification itself.
Thailand has established manufacturing depth in automotive, electronics, food, and industrial production. This supports demand for both factory modernization and replacement of aging automation assets. Indonesia presents a different mix, with large-scale domestic demand and industrial activity across consumer products, food processing, chemicals, mining-linked sectors, and infrastructure-related production. Geographic dispersion, logistics, site conditions, and service coverage can materially affect equipment selection there.
Malaysia’s manufacturing base includes electrical and electronics activity, process industries, and export-oriented production. It can be a relevant market for precision automation, test and inspection systems, industrial power solutions, and upgrades that support compliance with customer-specific manufacturing requirements. Across all markets, executives should avoid applying a regional headline to a local plant without checking its actual production constraints.
Risks That Can Undermine an Automation Project
The most common mistake is treating automation as a standalone equipment purchase. A robot, vision system, or software platform may perform well in a demonstration but fail to deliver on the production floor if inputs are inconsistent. Parts may arrive in different orientations, raw materials may vary, fixtures may be worn, or upstream processes may not hold tolerances. Automation tends to expose process instability; it does not reliably hide it.
Integration risk is particularly significant in brownfield factories. Older equipment may use proprietary interfaces, incomplete documentation, or control components that are no longer readily available. Before committing to a project, technical teams should map the installed base, identify communication protocols, verify electrical capacity, assess available floor space, and clarify who is responsible for each interface. A vague boundary between machine builder, system integrator, software provider, and plant engineering team can quickly become an expensive source of delay.
Cybersecurity is no longer limited to corporate IT. When machines are connected to plant networks, remote support tools, cloud dashboards, or enterprise systems, access control and network segmentation require attention. The appropriate approach depends on plant architecture and risk exposure, but leaders should ask early how user roles, backups, remote connections, patches, and incident response will be managed. Retrofitting these controls after commissioning is usually harder.
There is also a people risk. A system may be technically sound but operationally fragile if only one programmer or external integrator understands it. Training should cover more than start-stop operation. Maintenance technicians need fault-finding logic, spare-parts procedures, safety awareness, and access to current documentation. Supervisors need to understand which production indicators matter and which alarms require escalation. This is where many return-on-investment calculations become too optimistic.
How Executives Can Evaluate Projects More Rigorously
A useful starting point is to define the operational outcome before selecting technology. “Add robots” is not a business requirement. “Reduce manual handling at a hazardous loading station while maintaining required throughput and allowing product changeovers” is closer to one. The latter gives engineering, procurement, and finance teams a basis for testing assumptions.
Project evaluation should include the full operating environment: product mix, takt time, rejection handling, planned changeovers, maintenance windows, floor conditions, compressed-air quality where relevant, electrical supply, safety guarding, and expected spare-parts lead times. For systems intended for export manufacturing, buyer specifications and destination-market requirements may also influence documentation, safety validation, traceability, and component choices. These requirements need confirmation against the relevant project and local rules rather than assumptions based on another market.
A phased approach is often more reliable than a large, undifferentiated transformation program. Plants can begin with one constrained process, document baseline performance, test integration methods, and build maintenance confidence. The goal is not to avoid ambitious projects; it is to make sure the organization learns from an initial deployment before repeating it across multiple lines or sites.
Procurement teams should look beyond initial equipment price. A lower-cost system can become more expensive when documentation is thin, programming support is distant, spare parts are difficult to obtain, or the controls platform is poorly matched to the plant’s existing skills. Conversely, a premium platform may be unnecessary for a stable, simple application. The right choice depends on lifecycle support, interface requirements, production criticality, and the cost of downtime.
Reading the Market Beyond the Equipment Catalogue
The industrial automation market in Southeast Asia should be viewed as an ecosystem rather than a list of devices. Equipment suppliers, component manufacturers, system integrators, software providers, electrical contractors, distributors, training partners, and plant engineering teams all influence whether an investment works over time. Local service capability and supply-chain visibility can be as important as a controller’s technical features.
For decision-makers tracking this market, the useful signals are not limited to broad growth forecasts. Watch where manufacturers are expanding capacity, which industrial sectors are upgrading quality systems, whether automation suppliers are strengthening local technical support, how component availability is changing, and where power, logistics, or skills constraints may delay deployment. Industry exhibitions, company developments, technology releases, and trade activity can provide early indications, but they need to be interpreted in the context of actual plant demand.
NEXUSINSIGHTS follows these connected developments across manufacturing machinery, industrial equipment, electrical systems, automation technologies, mechanical components, and global industrial supply chains. For manufacturers, exporters, procurement teams, EPC contractors, engineers, and investors, the value of market intelligence lies in connecting equipment trends with sourcing conditions, local industrial movement, and the practical constraints of implementation.
Southeast Asia will continue to attract automation investment, but the most durable opportunities will not come from copying a standardized factory model. They will come from matching technology to a specific process problem, checking the local support and integration environment, and treating workforce capability, data governance, and lifecycle maintenance as part of the original investment decision.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.
- industrial equipment
- manufacturing machinery
- industrial supply
- procurement
- manufacturing
- equipment suppliers
- industrial robots
- sensors
- production capacity
- industrial supply chains
- mechanical components
- electrical systems
- industrial automation market
- condition monitoring
- manufacturing capacity
- equipment selection
- factory modernization
- industrial automation market in Southeast Asia