Heavy machinery market updates suggest orders are turning selective

Heavy machinery market updates indicate buyers are becoming more selective as cost pressure, project timing, and technology upgrades reshape demand. From construction equipment market signals and excavator industry news to iron ore market shifts, mineral price trends, and industrial automation news, this overview helps researchers, operators, buyers, and decision-makers track the forces influencing orders, investment priorities, and near-term opportunities across industrial sectors.
Across manufacturing, processing machinery, industrial components, and electrical equipment supply chains, order behavior is no longer driven by volume alone. Buyers are comparing lead times, fuel efficiency, maintenance intervals, automation readiness, and raw material exposure before approving new equipment budgets. For procurement teams and executives, the market is not necessarily weak, but it is more disciplined, more segmented, and more sensitive to total lifecycle value.
That shift matters because heavy equipment decisions often lock in capital, service commitments, and operational performance for 5-10 years. A delayed mine expansion, a slower property cycle, or a higher steel input cost can quickly change the payback case for excavators, loaders, crushing systems, power units, and workshop machinery. Selective ordering is therefore becoming a practical response to tighter cash control and a stronger demand for measurable returns.
Why heavy machinery orders are turning selective
The first reason is cost visibility. Buyers are watching not only purchase price, but also freight, spare parts, labor, and energy consumption over a 12-36 month horizon. In many industrial sectors, a machine that is 8% cheaper upfront may become 10%-15% more expensive in operation if fuel burn, wear parts, and downtime are not controlled. This is especially relevant in construction equipment market planning and in export-oriented factories where utilization rates can change quarter by quarter.
The second reason is project timing. Orders linked to infrastructure, mining, and plant expansion now face more staged approvals. Instead of committing to a full fleet in one cycle, many buyers are splitting orders into 2 or 3 phases. A contractor may secure 6 machines now and leave another 4 under review until financing, subcontractor progress, or site readiness becomes clearer. That behavior makes order books look uneven even when end-use demand still exists.
The third reason is technology transition. Buyers increasingly ask whether a machine can support telematics, predictive maintenance, hybrid drives, automated control interfaces, or easier integration with industrial automation systems. This is one reason industrial automation news now influences heavy equipment buying more directly than before. The machine itself is still the core asset, but the data capability around it is becoming part of the purchasing decision.
A more selective market does not mean all product categories are slowing at the same pace. Demand can remain active in replacement cycles, quarry operations, energy projects, and export production while softening in speculative construction or low-margin capacity expansion. The result is a mixed market where suppliers need better segmentation and buyers need clearer selection criteria.
Key filters buyers are applying
- Expected utilization above 65%-75% over the next 6-12 months.
- Maintenance intervals long enough to reduce service stoppages, often targeting 250-500 operating hours between routine checks.
- Lead times that fit project windows, typically under 4-12 weeks for standard units and under 16-24 weeks for configured systems.
- Availability of critical spare parts within 24-72 hours in major operating regions.
These filters are reshaping negotiations. Suppliers that can explain operating economics, service coverage, and integration options are more likely to secure deals than those competing only on list price.
Construction equipment, excavator demand, and fleet replacement signals
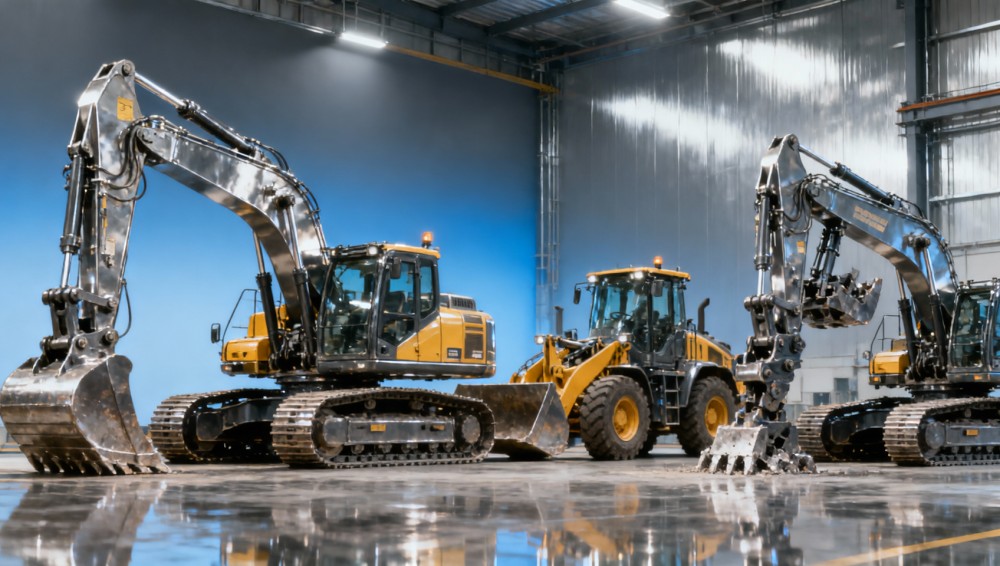
Construction equipment market activity remains one of the clearest indicators for heavy machinery demand, but the signal is fragmented. Buyers are still active in roadworks, utility upgrades, quarry feeding, and municipal projects, while some private development segments remain cautious. Excavator industry news reflects this split: compact and mid-size units may hold steadier demand in mixed-use jobs, while larger units depend more heavily on mining, infrastructure packages, and bulk earthwork schedules.
Fleet replacement is also becoming more analytical. Many operators now compare refurbishment versus replacement at the 6,000-10,000 hour mark, depending on application severity. If engine efficiency drops, hydraulic response slows, or unplanned downtime exceeds 3%-5% of scheduled operating time, replacement discussions move faster. However, if parts access is good and rebuild economics remain within 50%-65% of the cost of a new machine, some users will extend asset life instead of ordering immediately.
For procurement managers, the most important issue is matching machine size and duty cycle to realistic workloads. Over-specification ties up capital and raises idle costs. Under-specification increases wear, operator fatigue, and cycle-time losses. In selective markets, the wrong configuration is harder to hide because every investment is under closer financial review.
Typical buying logic by application
The table below shows how different use cases affect equipment choice, budgeting pace, and service priorities. It is particularly useful for buyers comparing near-term order decisions across contracting, mining support, and factory-linked material handling.
The key takeaway is that demand still exists, but it is concentrated where project visibility and machine utilization are easier to defend. Suppliers serving these active niches should emphasize uptime metrics, application fit, and service readiness rather than broad market claims.
Common selection mistakes in current market conditions
- Choosing solely by sticker price without reviewing fuel, tires, filters, and wear parts over the first 1,000 operating hours.
- Ordering oversized capacity for uncertain projects, which lowers asset turnover.
- Ignoring training needs for operators when switching to newer control systems or semi-automated functions.
In a selective order environment, correcting these mistakes can improve payback discipline as much as negotiating a lower purchase price.
Raw materials, iron ore, and mineral price trends shaping equipment investment
Iron ore market moves and broader mineral price trends remain important because they influence both customer confidence and supplier cost structures. When ore prices are stable or improving, mining-linked demand for excavators, haul support equipment, screening systems, and replacement wear parts can strengthen. When prices become volatile, operators often protect cash by delaying non-essential fleet additions and shifting spending toward maintenance or component rebuilds.
Raw material pricing also affects machinery manufacturing itself. Steel plate, cast components, bearings, copper content in electrical systems, and freight charges can all change quotations within a 30-90 day window. That means procurement teams should review quote validity periods carefully. A machine quoted today may hold price for only 15, 30, or 45 days depending on material exposure and supplier inventory coverage.
For industrial buyers, the practical question is not whether raw material prices move, but how much that movement can be passed through. Suppliers with better sourcing discipline, local inventory, or modular designs are often more resilient. Buyers should therefore compare not only equipment specifications but also quotation terms, escalation clauses, and spare-part pricing logic.
This is where market analysis and supply chain intelligence become highly valuable. A selective order market rewards planning. If mineral price trends support output growth but equipment lead times remain long, buyers may place smaller anchoring orders first and lock service parts separately to reduce risk.
How raw material shifts translate into buying behavior
The following comparison summarizes how input-cost and commodity conditions can affect order timing, negotiation strategy, and preferred contract structure across industrial equipment categories.
The practical conclusion is simple: equipment demand and raw material markets are now more tightly connected in boardroom decisions. Procurement teams should monitor commodity-linked timing because even a 4-8 week delay can alter pricing, lead time, or financing assumptions.
Industrial automation is changing what buyers expect from heavy equipment
Industrial automation news matters because heavy machinery is no longer judged only by mechanical output. Buyers increasingly expect digital diagnostics, remote monitoring, fault alerts, and easier data exchange with plant or fleet management systems. In practical terms, a buyer comparing two similar units may choose the one with stronger sensor coverage, clearer maintenance dashboards, and lower troubleshooting time, even if the base price is slightly higher.
For operators and maintenance teams, automation can reduce avoidable downtime. Basic telematics may support fuel tracking, idle-time analysis, and service reminders at 250-hour or 500-hour intervals. More advanced systems can help identify overload patterns, hydraulic anomalies, or recurring temperature issues before they turn into major failures. This is particularly relevant in high-use environments where one unplanned stoppage can disrupt several linked processes.
Decision-makers should still remain practical. Not every site needs the most advanced automation package. The right question is whether digital features solve a real operational problem. On a fleet of 3 machines, a simple monitoring suite may be enough. On a network of 30-50 units spread across multiple projects, centralized visibility can justify a more advanced investment.
What buyers should evaluate in automation-ready machinery
- Data visibility: Can operators and managers access fuel use, hours, fault codes, and service reminders from one interface?
- Integration practicality: Does the equipment support common control and monitoring workflows without a long custom setup cycle?
- Training burden: Can operators become productive within 1-3 shifts, or does the system require extensive retraining?
- Service value: Will remote diagnostics reduce travel, troubleshooting time, or unnecessary part replacement?
A useful rule is to compare digital features against measurable outcomes such as downtime reduction, fuel savings, or maintenance planning accuracy. If the supplier cannot link features to operational impact, the value proposition may be incomplete.
Three realistic adoption paths
- Entry level: basic hour tracking, GPS, and service reminders for smaller fleets or first-time digital users.
- Mid level: fault analytics, utilization reports, and remote support for multi-site contractors and busy workshops.
- Advanced: data integration with production planning, inventory, or centralized asset systems for larger industrial groups.
The selective order trend favors suppliers that offer modular automation choices rather than forcing a single package on every buyer.
Procurement strategy, risk control, and near-term opportunities
In the current market, procurement strategy needs to balance urgency with flexibility. Buyers should define whether the machine is revenue-critical, replacement-critical, or optional. Revenue-critical assets support immediate contracts or output commitments. Replacement-critical assets prevent downtime from aging fleets. Optional assets may improve efficiency but can wait if cash discipline is tight. This simple 3-tier framework helps avoid rushed purchasing in volatile conditions.
Lead time mapping is equally important. Standard equipment may ship in 2-8 weeks, but configured systems, electrical upgrades, or imported assemblies can extend delivery to 12-24 weeks. For supply chain intelligence purposes, buyers should separate long-cycle parts from the main equipment purchase. Securing motors, control components, wear parts, or hydraulic assemblies early can reduce commissioning risk later.
Another opportunity lies in service-led purchasing. In a selective market, the winning supplier may not be the cheapest one, but the one that can keep equipment productive. A clearly defined spare parts package for the first 6-12 months, operator training, and maintenance response commitments often create more value than a small discount on the base machine.
Procurement checklist for selective order conditions
The table below can be used by buyers, plant managers, and decision-makers as a quick screening tool before approving machinery orders in manufacturing, mining support, construction, or material handling applications.
This checklist highlights a central theme in heavy machinery market updates: buyers are still willing to invest, but they expect stronger proof on uptime, serviceability, and timing before they commit.
Near-term opportunities suppliers should watch
- Replacement demand in fleets older than 7-10 years where repair frequency is rising.
- Quarry, aggregate, and mineral handling upgrades driven by wear-part economics and output targets.
- Factory-side material handling and power support equipment tied to automation retrofits.
- Export trade developments that create demand for robust, serviceable machinery rather than premium-only specifications.
For market participants following industry news, company developments, exhibitions, and supply chain changes, the most useful approach is to connect each headline back to a procurement question: does it improve timing, reduce cost risk, or increase asset productivity?
FAQ: practical questions buyers are asking
How should buyers choose between immediate purchase and phased ordering?
If project visibility is below 70% or financing remains uncertain, phased ordering is often safer. Secure revenue-critical units first, then review the next batch after 30-90 days. This protects cash flow while preserving operational flexibility.
What indicators suggest a machine should be replaced rather than rebuilt?
Typical warning signs include rising downtime, repeated hydraulic or engine issues, poor fuel efficiency, and rebuild costs approaching 50%-65% of a new machine price. Operating-hour history and parts availability should be reviewed together, not separately.
How long is a normal delivery cycle for heavy industrial equipment?
For standard units, 2-8 weeks is common. Configured machinery, imported electrical systems, or project-specific components can extend lead times to 12-24 weeks. Buyers should confirm whether commissioning support is included in the same timeline.
Which metrics matter most in a selective market?
Four metrics stand out: expected utilization, service response time, operating cost per hour, and delivery certainty. These metrics often explain long-term value better than headline price alone.
Heavy machinery market updates now point to a market that is disciplined rather than inactive. Construction equipment demand, excavator replacement logic, iron ore market direction, mineral price trends, and industrial automation developments are all influencing how orders are evaluated. Buyers are asking sharper questions about lifecycle cost, timing, digital capability, and service readiness before approving capital spend.
For researchers, operators, procurement teams, and business leaders, the opportunity is to make better decisions with clearer market signals and stronger comparison frameworks. If you want support tracking equipment trends, supply chain intelligence, price movements, or category-specific sourcing options across manufacturing and industrial sectors, contact us to get tailored insights, discuss product details, or explore more solutions for your next purchasing cycle.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.