Electrical Transformers Export Market: Key Regions, Demand Shifts, and Trade Risks
If you are assessing the electrical transformers export market, the main question is not simply where demand exists. The more useful question is where demand is investable, repeatable, and commercially workable after you factor in grid spending cycles, local certification, freight exposure, and trade policy risk. That is where many evaluations go wrong. A market can look attractive on paper and still be difficult to serve profitably.
Right now, export opportunities are being pulled in several directions at once. Utilities are upgrading aging transmission and distribution networks. Renewable integration is changing transformer specifications in many countries. Industrial expansion is supporting some segments, while construction slowdowns and currency pressure are weakening others. At the same time, buyers are becoming more cautious about lead times, supplier concentration, and compliance documentation.
In practical terms, the electrical transformers export market is no longer a story of broad global growth. It is a story of uneven regional demand, selective project pipelines, and higher execution risk.
What is really moving the market now
A short answer first: the strongest export opportunities tend to be in regions where grid investment, industrial power demand, and public infrastructure spending are moving at the same time. Demand is softer or more unpredictable where capital spending is delayed, local protection measures are rising, or buyers are postponing procurement because of financing pressure.
That sounds obvious, but in transformer trade it matters more than in many other equipment categories. Electrical transformers are not easy to substitute at the last minute. Specifications, insulation class, cooling method, efficiency standards, voltage ratings, and testing requirements all affect whether a supplier can actually convert demand into shipped orders. So when buyers change plans, exporters feel it quickly.
One common mistake is to read the market only through headline energy investment. Grid expansion may be real, but the export window depends on procurement structure. Some countries favor international bidding; others effectively protect local assembly or require a high local-content share. A healthy project pipeline does not automatically mean a healthy export market.
Key regions in the electrical transformers export market
Asia remains central, both as a manufacturing base and as a destination for specific transformer types. The region is not one market. Fast-growing economies in South and Southeast Asia continue to invest in transmission, urban distribution networks, industrial zones, and power reliability. That supports demand for power transformers, distribution transformers, and related substation equipment. At the same time, competition is intense, price sensitivity is high, and local supplier ecosystems are often stronger than new entrants expect.
The Middle East is still one of the more interesting regions for export-oriented suppliers, especially where utility expansion, urban development, desalination, industrial diversification, and renewable integration are happening together. The opportunity is real, but qualification standards can be demanding, project cycles can be long, and vendor approval is often as important as price.
Africa offers pockets of strong demand tied to electrification, utility rehabilitation, mining, and industrial development. But this is where inexperienced evaluators often overestimate near-term volume. The need is large; the procurement reality can be slower, more fragmented, and more finance-dependent. Credit risk, tender delays, and after-sales service expectations need closer scrutiny than the topline demand numbers suggest.
Europe has demand drivers linked to grid modernization, energy transition, and replacement of aging installed bases. Still, exporters face a more complex environment here. Efficiency rules, product conformity, technical documentation, and traceability expectations are generally stricter. Buyers are also more alert to lifecycle performance, not just acquisition cost. For qualified exporters, that can support better margins. For underprepared suppliers, it can become a costly market-entry exercise.
North America remains important, especially where infrastructure investment and utility replacement programs are active. Yet it is not an easy export market to enter casually. Testing standards, customer approval procedures, domestic preference issues, and geopolitical trade sensitivities all influence access. In some cases, the opportunity is stronger for component supply, partnerships, or partial localization than for straightforward finished-unit exports.
Latin America continues to present mixed signals. Some markets benefit from grid expansion, mining, industrial projects, and renewable generation development. Others are affected by fiscal pressure, currency volatility, and shifting import conditions. It is often a region where timing matters more than broad optimism. A country can move from active procurement to delayed purchasing within a short policy cycle.
[图片占位符1:A regional trade map highlighting major destination areas, demand intensity, and risk zones in the electrical transformers export market, alt="regional overview of the electrical transformers export market and demand shifts"]
Demand is shifting, but not evenly
The biggest shift is not just more demand. It is demand becoming more specific.
Utilities are asking harder questions about efficiency, temperature rise, overload performance, digital monitoring compatibility, and reliability under unstable grid conditions. Renewable-heavy systems can require different planning assumptions than conventional generation networks. Industrial buyers may prioritize delivery certainty and service support over the lowest initial quote. In export terms, this means the market is fragmenting by use case, not just geography.
Another change is the growing importance of replacement demand. In mature markets, old assets are a major driver. In developing markets, new network build-out still matters, but replacement and rehabilitation are becoming more visible as installed bases age and maintenance gaps catch up. That tends to favor suppliers who can document performance, reference projects, and testing discipline.
There is also a lead-time story behind current demand. In periods when large manufacturers are backlogged, buyers often widen their supplier search. That creates openings for secondary exporters. But these openings can close quickly once capacity normalizes. For a business evaluation, it is risky to treat emergency sourcing demand as a stable market trend.
Where evaluations often miss the real risk
Trade risk in this market is not limited to tariffs. In fact, tariffs are often only the visible part.
Start with technical compliance risk. A transformer that is acceptable in one country may require different test reports, efficiency levels, insulation materials, or certification formats in another. If those requirements are discovered late, margins erode fast. Rework, retesting, shipment delay, and customs friction can undo an otherwise attractive deal.
Then there is raw material and pricing risk. Transformer costs are highly exposed to copper, electrical steel, insulating materials, and freight. Even when the final order value looks solid, margin stability may be weak if the contract structure does not handle cost movement well. Evaluators should pay attention to quote validity windows, material escalation clauses, and the supplier’s procurement discipline.
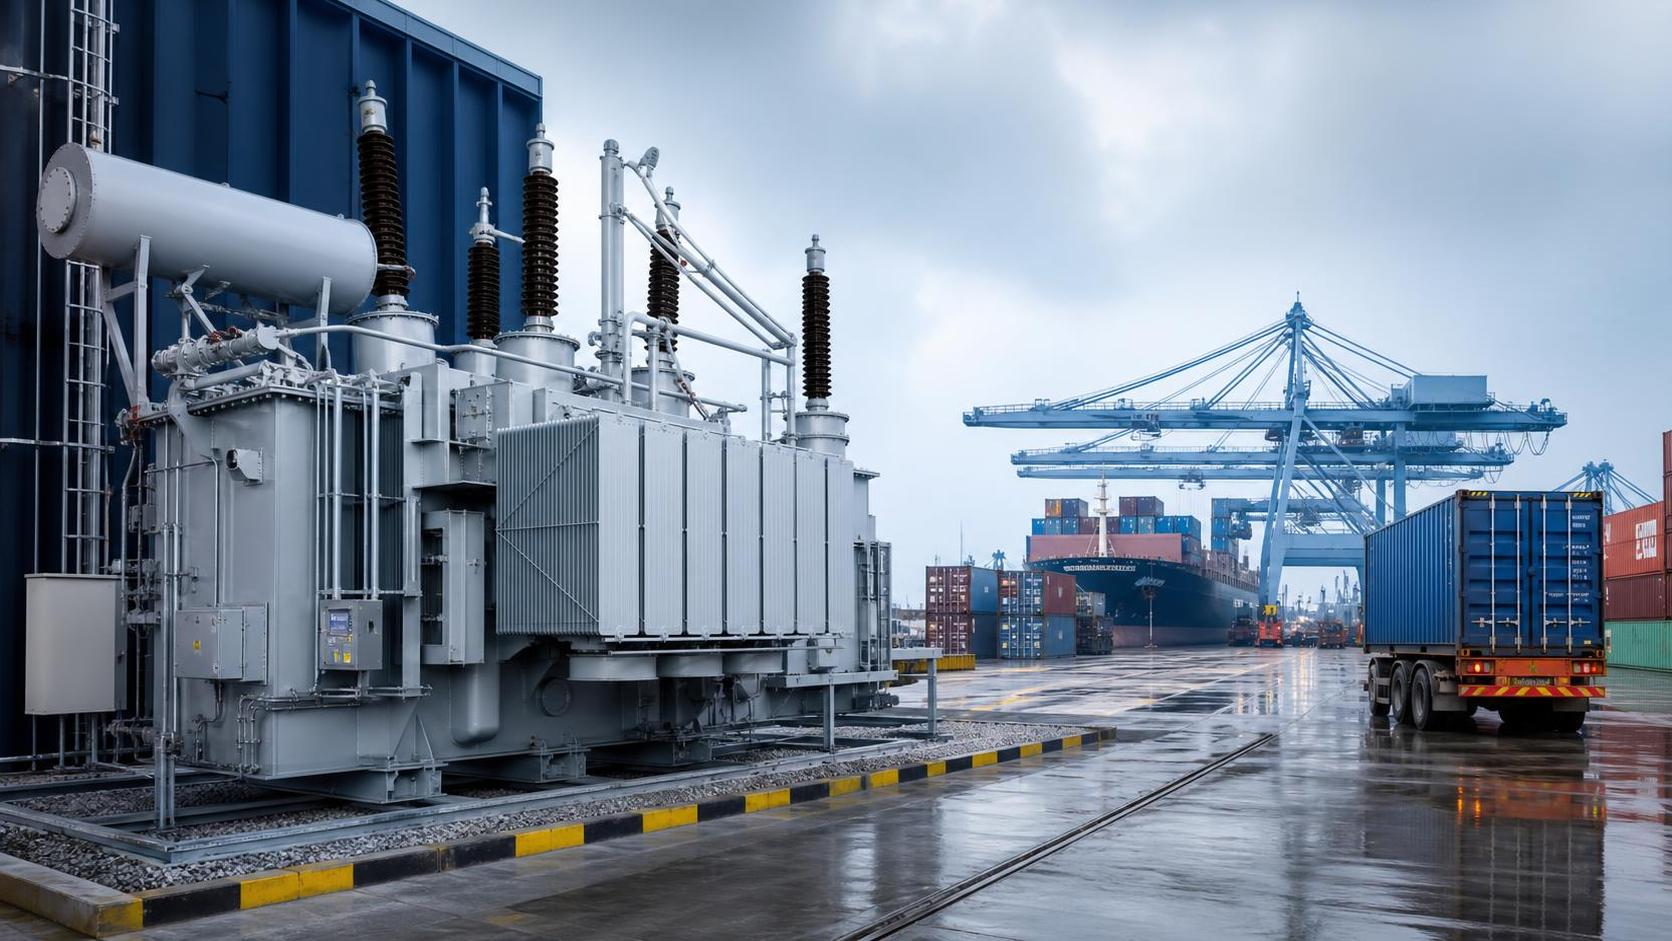
Logistics risk is another blind spot. Large transformers are not routine cargo. Port handling capability, inland transport restrictions, packaging standards, route surveys, and insurance terms can materially change landed cost and delivery feasibility. A destination market may seem attractive until oversized cargo constraints are added to the model.
Policy risk also deserves a more granular view. Import licensing changes, customs scrutiny, sanctions exposure, anti-dumping actions, public procurement preference rules, and local-content requirements can all reshape the economics of export sales. These do not hit every transformer class equally, and they do not hit every country equally. A broad “trade tension” label is not enough for decision-making.
Finally, there is counterparty risk. In some markets, especially where public utilities are under financial pressure, delayed payment can be more damaging than a lower selling price. A supplier that wins orders but struggles to collect is not in a strong market position.
What buyers are doing differently
Many buyers now want optionality. They are qualifying more than one geography, more than one production base, and more than one supplier tier. This does not mean they are abandoning long-term partnerships. It means they are trying to reduce dependence on a single source in a category where delivery delays can stall larger projects.
That shift changes how exporters should be assessed. The strongest candidates are not always the cheapest or the biggest. Often they are the ones with acceptable technical depth, steady documentation, realistic lead times, and enough operational discipline to support tender requirements and post-shipment issues.
It also means market evaluation should not stop at import volume or growth language. The better question is whether a supplier can survive the buyer’s approval process and the destination market’s execution demands.
A practical way to read this market
For business users reviewing the electrical transformers export market, a useful framework is to test each target region across five filters:
- Demand quality: Is spending driven by confirmed utility or industrial programs, or mainly by optimistic projections?
- Access difficulty: How hard is certification, vendor registration, and specification matching?
- Price resilience: Can margins survive raw material swings and freight volatility?
- Trade friction: Are there policy, customs, sanctions, or local-content barriers that could reduce competitiveness?
- Service reality: Can the supplier support installation, warranty response, spares, or technical clarification when problems arise?
This kind of filter often gives a clearer answer than market-size estimates alone. A smaller but accessible market can be commercially better than a large market with heavy qualification barriers and unstable payment conditions.
In actual market tracking work, this is also where information quality matters. Platforms such as NEXUSINSIGHTS can be useful when teams need to follow industrial market movements, equipment trends, policy changes, and global supply chain signals across electrical and broader industrial sectors. That kind of visibility helps, especially when a transformer opportunity depends on factors outside the transformer category itself, such as grid policy, project activity, or industrial investment cycles.
Common misunderstandings worth clearing up
One misunderstanding is that rising renewable energy investment automatically boosts all transformer exporters. It can support demand, yes, but the benefit depends on grid architecture, interconnection projects, substation build-out, and procurement channels. Some of that demand is accessible to exporters; some is captured by approved domestic or regional suppliers.
Another is that distribution transformers and power transformers should be assessed the same way. They should not. Sales cycles, buyer profiles, transport complexity, tender requirements, and after-sales expectations can differ materially. A company that performs well in one segment may not transfer that strength cleanly into the other.
A third is that lower manufacturing cost always wins export business. In this market, documentation quality, testing credibility, and delivery predictability often decide the order. Cheap pricing can help secure attention, but it does not fix qualification gaps.
What to verify before making a market call
Before concluding that a region is attractive, confirm a few basics. Check whether demand is tied to funded projects or still at announcement stage. Verify applicable technical and import requirements through official channels or project documents. Stress-test landed cost under different freight and material scenarios. Review whether the target customers buy directly, through EPC contractors, through distributors, or through utility tenders. That procurement route changes the sales strategy.
Also, be careful with broad forecasts that are not backed by transparent methodology. In this sector, timing matters. A six-month delay in grid tenders or project financing can distort a yearly export plan.
Near the end of any assessment, one question usually clarifies the picture: is the opportunity driven by structural demand or temporary shortage? Structural demand can justify long-term market development. Temporary shortage may justify tactical sales, but not heavy commitment.
The electrical transformers export market still offers real opportunity, especially in regions where grid reliability, industrial expansion, and energy transition projects are moving forward together. But the best decisions come from separating visible demand from executable demand. That means looking past headline growth and testing each market for compliance burden, policy friction, logistics feasibility, and payment quality before treating it as a serious export target.
FAQ
Which region looks most attractive for transformer exports right now?
There is no single best region across all product types. Parts of Asia and the Middle East often show stronger near-term potential, but suitability depends on your transformer segment, certification readiness, and route to market.
Are trade risks mainly about tariffs?
No. Technical compliance, customs treatment, local-content rules, sanctions exposure, freight constraints, and payment risk can be just as important as tariff levels.
Does renewable energy growth always increase transformer export opportunities?
Not automatically. The export impact depends on whether renewable investment is translating into grid projects and whether procurement is open to foreign suppliers.
What is the biggest mistake in evaluating this market?
Confusing broad infrastructure need with accessible export demand. A market may need transformers badly and still be difficult to enter or serve profitably.
Image Placeholder List
- 图片占位符1:Suggested near the regional analysis section; content shows a trade map with demand hotspots and risk zones; alt="regional overview of the electrical transformers export market and demand shifts"
Internal Link Anchor Text Suggestions
- Transformer sourcing risk assessment: sourcing strategy or procurement analysis page
- Global power equipment market trends: electrical equipment industry insights page
- Industrial export compliance checklist: trade compliance or documentation guide page
- Grid infrastructure investment outlook: energy infrastructure market analysis page
- Distribution transformer vs power transformer demand: product segment comparison page
External Authority Source Suggestions
- Government trade and customs authority pages for import rules, tariffs, and product classification
- Power sector industry association reports covering grid investment and transformer demand trends
- Official utility tender portals or multilateral development project databases for funded infrastructure activity
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.